Your PSLF payment count after consolidation is not reset to zero, but it is averaged across every loan you combine, and that average can cost you years of progress.
KEY TAKEAWAYS
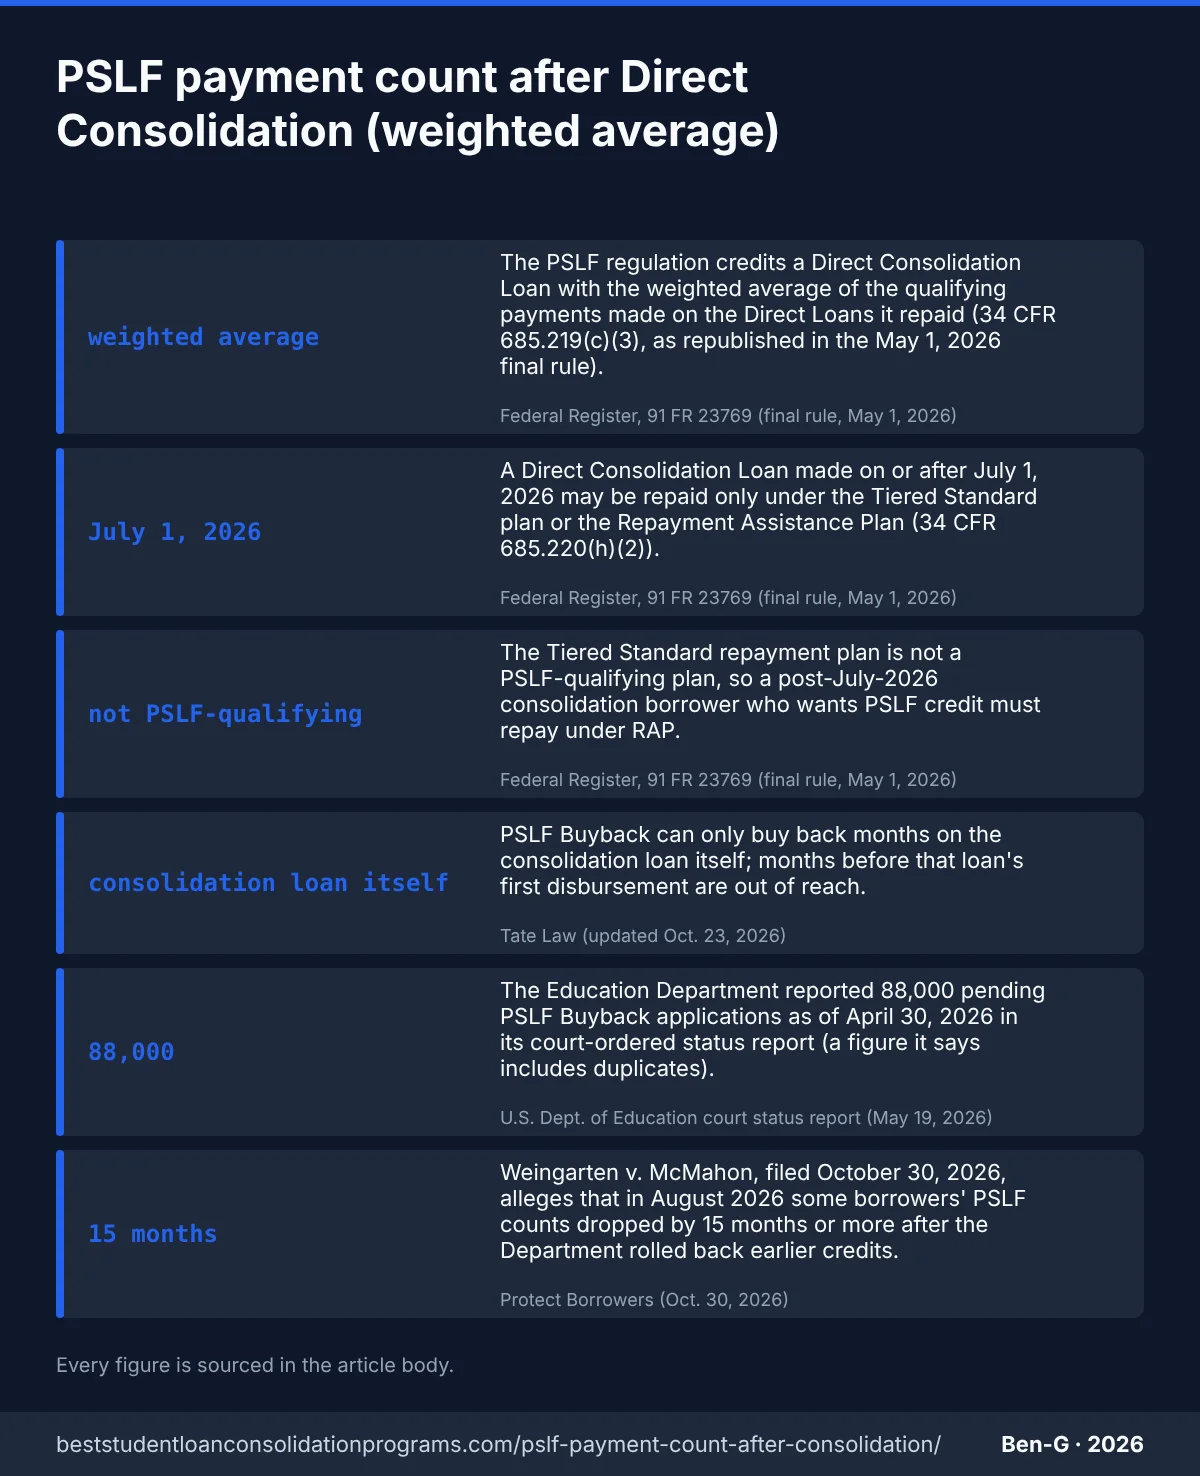
- → weighted average The PSLF regulation credits a Direct Consolidation Loan with the weighted average of the qualifying payments made on the Direct Loans it repaid (34 CFR 685.219(c)(3), as republished in the May 1, 2026 final rule). (Federal Register, 91 FR 23769 (final rule, May 1, 2026), 2026)
- → July 1, 2026 A Direct Consolidation Loan made on or after July 1, 2026 may be repaid only under the Tiered Standard plan or the Repayment Assistance Plan (34 CFR 685.220(h)(2)). (Federal Register, 91 FR 23769 (final rule, May 1, 2026), 2026)
- → not PSLF-qualifying The Tiered Standard repayment plan is not a PSLF-qualifying plan, so a post-July-2026 consolidation borrower who wants PSLF credit must repay under RAP. (Federal Register, 91 FR 23769 (final rule, May 1, 2026), 2026)
- → consolidation loan itself PSLF Buyback can only buy back months on the consolidation loan itself; months before that loan's first disbursement are out of reach. (Tate Law (updated Oct. 23, 2026), 2026)
- → 88,000 The Education Department reported 88,000 pending PSLF Buyback applications as of April 30, 2026 in its court-ordered status report (a figure it says includes duplicates). (U.S. Dept. of Education court status report (May 19, 2026), 2026)
- → 15 months Weingarten v. McMahon, filed October 30, 2026, alleges that in August 2026 some borrowers' PSLF counts dropped by 15 months or more after the Department rolled back earlier credits. (Protect Borrowers (Oct. 30, 2026), 2026)
- → 20 A $15,000 loan with 100 qualifying payments consolidated with a $60,000 loan at zero blends down to 20 qualifying payments (The College Investor's worked example). (The College Investor (updated Feb. 1, 2026), 2026)
Your PSLF payment count after consolidation no longer resets to zero, but consolidating does something most borrowers only discover after the fact: it blends every Direct Loan’s count into one balance-weighted number. Federal Student Aid’s own illustration shows how sharp the blend can be. A borrower with sixty qualifying payments on one loan, consolidating it with an equal-sized loan that has none, is credited 30 payments on the new loan (Federal Student Aid (studentaid.gov), 2026). Half the progress is still there; half of it has been averaged away.
That is the rule. What has been missing is the arithmetic for the loan mixes people actually hold, and the three other costs that a consolidation completed on or after July 1, 2026 now carries: the plans the new loan is allowed to use, the forgiveness clock that no longer travels with it, and the Buyback months that fall out of reach. This page works through all of it from the regulation itself, the Department’s court-ordered reporting, and the attorneys and calculators borrowers rely on. Every number links to where it came from, and the rows marked as our calculation say so.
The short version: if every Direct Loan you consolidate carries the same count, you lose nothing. If one seasoned loan is blended with a larger loan that has little credit, the loss can be most of what you earned, and since July 2026 the decision cannot be undone by switching back to an older plan. The pages at Best Student Loan Consolidation Programs exist to make that trade visible before you sign.
1 How Much of Your PSLF Payment Count After Consolidation Do You Keep? Six Worked Loan Mixes
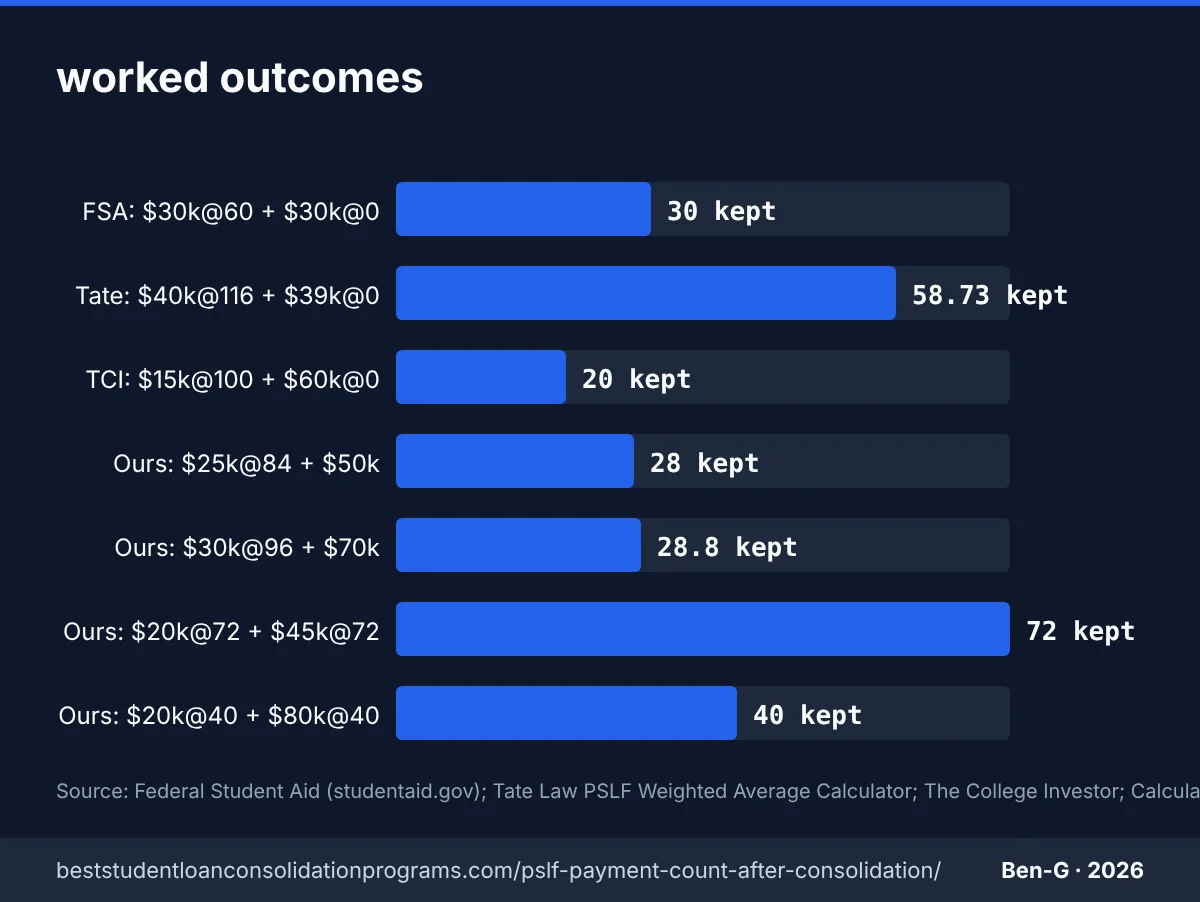
The formula is simple: multiply each Direct Loan’s balance by its qualifying-payment count, add the products, divide by the total balance. FSA’s example yields 30; The College Investor’s yields 20; Tate Law’s calculator yields 58.73. Equal counts keep everything; a large zero-count loan erases most of it. (Federal Student Aid (studentaid.gov), 2026)
| LOAN MIX | PAYMENTS CREDITED AFTER CONSOLIDATION | SOURCE |
|---|---|---|
| FSA example: $30,000 at 60 payments + $30,000 at 0 | 30 | Federal Student Aid (studentaid.gov) |
| College Investor example: $15,000 at 100 + $60,000 at 0 | 20 | The College Investor |
| Tate Law example: $40,000 at 116 + $39,000 at 0 (unrounded) | 58.73 | Tate Law PSLF Weighted Average Calculator |
| Our calculation: $25,000 Direct at 84 + $50,000 FFEL at 0 | 28 | Calculated from 34 CFR 685.219(c)(3) formula |
| Our calculation: $30,000 Direct at 96 + $70,000 Parent PLUS at 0 (unrounded) | 28.8 | Calculated from 34 CFR 685.219(c)(3) formula |
| Our calculation: $20,000 at 72 + $45,000 at 72 | 72 | Calculated from 34 CFR 685.219(c)(3) formula |
| Our calculation: $20,000 at 40 + $80,000 at 40 | 40 | Calculated from 34 CFR 685.219(c)(3) formula |
Read the table from the bottom up and the pattern is obvious. The two rows where every loan carries the same count, 72 and 40, lose nothing, and the balances do not matter at all. The damage appears only when counts differ, and it scales with the share of the total balance held by the loan with the lower count. In The College Investor’s example the seasoned loan is a fifth of the total, so four fifths of its hundred payments disappear and 20 remain (The College Investor, 2026). In FSA’s example the two loans are equal, so exactly half survives.
The two rows we calculated ourselves are the ones borrowers ask about most on r/PSLF and r/StudentLoans: a Direct Loan with years of credit sitting next to an older FFEL loan, or a Parent PLUS loan that has never been in a qualifying plan. The regulation is explicit that only payments on the Direct Loans being consolidated enter the average, and that Direct PLUS Loans made to parents are included in the blend (Federal Register, 91 FR 23769 (34 CFR 685.219(c)(3)), 2026). FSA’s FAQ adds the other half of the sentence: other loan types will not be considered (Federal Student Aid (studentaid.gov), 2026). So a FFEL balance contributes its full weight to the denominator and nothing to the numerator, which is why the Direct-plus-FFEL row falls from eighty-four to 28.
One number in the table deserves its own caveat. Tate Law shows 58.73 unrounded because the PSLF regulation does not say how the Department rounds (Tate Law PSLF Weighted Average Calculator, 2026). The IDR-forgiveness paragraph, by contrast, rounds its weighted average up to the nearest whole month (Federal Register, 91 FR 23769 (final rule, May 1, 2026), 2026). Until FSA publishes its PSLF rounding, treat a fractional result as a floor, not a promise. The calculator further down this page uses the same unrounded arithmetic so you can test your own mix.
2 What Exactly Does 34 CFR 685.219(c)(3) Say, and Since When?
The May 2026 final rule republishes the PSLF consolidation paragraph unchanged in substance: the new loan is credited the weighted average of qualifying payments made on the Direct Loans it repaid, parent PLUS included. The weighted average replaced the waiver-era highest-count treatment, which ended with the June 30, 2024 consolidation deadline. (Federal Register, 91 FR 23769 (34 CFR 685.219(c)(3)), 2026)
| RULE ELEMENT | WHAT IT SAYS | SOURCE |
|---|---|---|
| PSLF credit on a Direct Consolidation Loan | weighted average | Federal Register, 91 FR 23769 (34 CFR 685.219(c)(3)) |
| Which payments enter the average | Direct Loan payments only; other loan types will not be considered | Federal Student Aid (studentaid.gov) |
| Rounding, PSLF paragraph | Regulation does not specify how ED rounds | Tate Law PSLF Weighted Average Calculator |
| Rounding, IBR-forgiveness paragraph | rounded up to the nearest whole month | Federal Register, 91 FR 23769 (final rule, May 1, 2026) |
| Weighted average became the permanent default | Sept. 1, 2024 | The College Investor (updated Feb. 1, 2026) |
| Last day to apply for the highest-count account adjustment | June 30, 2024 | NASFAA (May 16, 2024) |
| Borrowers forgiven under the limited waiver that preceded it | 758,800 | The College Investor (updated Feb. 1, 2026) |
The rule has changed three times in five years, which explains why so much advice on forums is simply out of date. Before the limited waiver, consolidation reset the count to zero. During the waiver and the one-time account adjustment that followed, the Department applied the credit of the most-seasoned loan to the whole consolidation; The College Investor reports 758,800 borrowers forgiven under the waiver alone (The College Investor (updated Feb. 1, 2026), 2023). That generous treatment closed with the June 30, 2024 application deadline (NASFAA (May 16, 2024), 2024), and The College Investor dates the weighted average as the permanent default from Sept. 1, 2024 (The College Investor (updated Feb. 1, 2026), 2024). The Department’s own FAQ page on this point is a JavaScript application our tools could not read, so that start date is attributed to secondary reporting rather than to FSA directly.
What the regulation does not do is distinguish between a consolidation you chose and one you were steered into. Several of the Reddit threads behind this article describe borrowers who consolidated in 2018 or 2020 on a servicer’s advice and later had restored credit questioned. The paragraph that governs their count today is the one in the table, and the Department has confirmed in litigation that some earlier waiver-era credits were deliberately rolled back, which is the subject of the final section.
3 What Changed on July 1, 2026 for a New Consolidation Loan?
A Direct Consolidation Loan made on or after July 1, 2026 may be repaid only under the Tiered Standard repayment plan, or the Repayment Assistance Plan. The Tiered Standard plan is not a PSLF-qualifying repayment plan, so PSLF credit on the new loan comes only from RAP, whose forgiveness threshold is 360 payments. ICR-plan payments stop counting after June 30, 2028. (Federal Register, 91 FR 23769 (34 CFR 685.220(h)(2)), 2026)
| POST-CUTOVER ELEMENT | RULE | SOURCE |
|---|---|---|
| Plans available on a consolidation loan made on/after July 1, 2026 | Tiered Standard repayment plan, or the Repayment Assistance Plan | Federal Register, 91 FR 23769 (34 CFR 685.220(h)(2)) |
| Tiered Standard plan and PSLF | not a PSLF-qualifying repayment plan | Federal Register, 91 FR 23769 (final rule preamble) |
| Last date an ICR-plan payment counts for PSLF | June 30, 2028 | Federal Register, 91 FR 23769 (final rule preamble) |
| RAP forgiveness threshold | 360 qualifying monthly payments over at least 30 years | Federal Register, 91 FR 23769 (34 CFR 685.209(k)(8)) |
| IDR-forgiveness credit on a post-cutover consolidation | generally does not carry prior IDR-forgiveness credit | Tate Law PSLF Weighted Average Calculator (Nov. 6, 2026) |
| Final rule effective date | July 1, 2026 | Federal Register (May 1, 2026) |
This is the part the weighted-average calculators do not show, and it changes the answer for anyone consolidating now. The PSLF count still blends exactly as before; the regulation’s consolidation paragraph was republished in the same final rule. But the loan receiving that blended count is a new loan, and under the amended statute a new consolidation loan has two plans available: Tiered Standard repayment plan, or the Repayment Assistance Plan (Federal Register, 91 FR 23769 (34 CFR 685.220(h)(2)), 2026). Since the Tiered Standard plan is not a PSLF-qualifying repayment plan (Federal Register, 91 FR 23769 (final rule preamble), 2026), a borrower who consolidates and wants PSLF credit has one path, RAP, and must stay on it.
Two further clocks are affected. First, payments made under the older income-contingent plans count for PSLF only if made on or before June 30, 2028 (Federal Register, 91 FR 23769 (final rule preamble), 2026), so even borrowers who did not consolidate face a plan change within two years. Second, the IDR-forgiveness credit that the IBR paragraph preserves through its own rounded-up weighted average lives in a plan the new loan cannot use; Tate Law’s reading is that a consolidation completed on or after the cutover generally does not carry prior IDR-forgiveness credit (Tate Law PSLF Weighted Average Calculator (Nov. 6, 2026), 2026). RAP’s own forgiveness requires 360 qualifying monthly payments over at least thirty years (Federal Register, 91 FR 23769 (34 CFR 685.209(k)(8)), 2026). For a borrower close to IDR forgiveness that is a different trade than the PSLF arithmetic alone suggests, and it is why The College Investor has been telling readers not to consolidate without understanding the plan consequences first.
The practical reading is that the weighted average is now the smaller of the two costs. A borrower whose Direct Loans all carry similar counts keeps their PSLF progress intact but still surrenders IBR, PAYE and ICR on the new loan. Whether that is acceptable depends on income, on how many of the 360 RAP payments would ever be needed, and on whether the consolidation was required at all. For FFEL and Perkins holders it usually is required, because those loans cannot qualify for PSLF unconsolidated; for Direct-only borrowers, the question is what consolidation buys that an employment certification does not.
4 How Far Back Can PSLF Buyback Reach After You Consolidate?
Only to the new loan’s first disbursement. Buyback applies to months on the consolidation loan itself, requires 120 months of certified qualifying employment first, and under the 2026 rule months spent in RAP are not eligible for reconsideration credit. A consolidation therefore fixes the earliest month you can ever buy back. (Tate Law (updated Oct. 23, 2026), 2026)
| BUYBACK RULE | VALUE | SOURCE |
|---|---|---|
| Which months a consolidation borrower can buy back | Months on the consolidation loan itself only | Tate Law (updated Oct. 23, 2026) |
| Qualifying employment required before applying | 120 months | Tate Law (updated Oct. 23, 2026) |
| Deferment or forbearance months while enrolled in RAP | not eligible for reconsideration credit | Federal Register, 91 FR 23769 (final rule preamble) |
Buyback is the remedy most borrowers reach for when the weighted average leaves them short of one hundred twenty, and it is weaker after a consolidation than before one. Tate Law’s guide states the limit directly: you can only buy back months on the consolidation loan itself, and nothing before that loan’s first disbursement (Tate Law (updated Oct. 23, 2026), 2026). The forbearance or deferment months on the underlying loans, including SAVE forbearance months that pre-date the consolidation, are not on the new loan and cannot be converted. The program also does nothing for employment: it requires 120 months of certified qualifying employment and converts non-payment months into payment months only (Tate Law (updated Oct. 23, 2026), 2026).
The 2026 final rule narrows the remedy once more for the plan a new consolidation loan must use. In its response to commenters the Department confirms that months in the Repayment Assistance Plan are not eligible for reconsideration credit, reasoning that the statute counts only on-time RAP payments and a borrower in deferment or forbearance has not made one (Federal Register, 91 FR 23769 (final rule preamble), 2026). Put the two rules together and a borrower who consolidates after July 2026 and later pauses payments on RAP has months that can be bought back from neither side of the consolidation date. That is the blind spot in most guides: the weighted average is a one-time loss, but the Buyback ceiling is permanent.
5 How Big Is the Buyback Backlog, and What Is the Lawsuit About?
The Department’s court-ordered report counted 88,000 pending Buyback applications on April 30, 2026, with 6,600 approvals and 11,500 PSLF discharges processed that month. Protect Borrowers says the queue stood at 49,000 a year earlier. Weingarten v. McMahon, filed October 30, 2026, alleges counts dropped by 15 months or more. (U.S. Department of Education status report (ECF 65, May 19, 2026), 2026)
| METRIC | VALUE | SOURCE |
|---|---|---|
| Pending Buyback applications, April 30, 2026 (includes duplicates) | 88,000 | U.S. Department of Education status report (ECF 65, May 19, 2026) |
| Buyback applications approved, April 2026 | 6,600 | U.S. Department of Education status report (ECF 65, May 19, 2026) |
| PSLF discharges processed, April 2026 | 11,500 | U.S. Department of Education status report (ECF 65, May 19, 2026) |
| Pending Buyback applications, April 2025 | 49,000 | Protect Borrowers (Oct. 30, 2026) |
| Pending Buyback applications reported to The Washington Post, October 2026 | 82,000 | Tate Law citing The Washington Post (Oct. 2026) |
| PSLF count reductions alleged for August 2026 | 15 months or more | Protect Borrowers (Oct. 30, 2026) |
The numbers in this section come from the Department’s own filings in an earlier suit over income-driven repayment processing. Its May 2026 status report lists 88,000 Buyback applications pending at the end of April, a figure it says includes roughly eighteen to nineteen thousand duplicates, alongside 6,600 approvals and 11,500 PSLF discharges in the month (U.S. Department of Education status report (ECF 65, May 19, 2026), 2026). At that approval pace the stated queue is roughly a year deep, and the Department has published no processing-time estimate. Tate Law reports a figure of 82,000 pending given to The Washington Post in October (Tate Law citing The Washington Post (Oct. 2026), 2026), while Protect Borrowers puts the April backlog at nearly ninety thousand, up from 49,000 twelve months before (Protect Borrowers (Oct. 30, 2026), 2025).
The lawsuit matters to the consolidation question for a specific reason. Protect Borrowers’ release says that in August 2026 some borrowers saw their PSLF counts fall by 15 months or more, and that the Department acknowledged some earlier waiver and account-adjustment credits were purposely rolled back (Protect Borrowers (Oct. 30, 2026), 2026). Many of those credits were awarded on consolidation loans under the highest-count treatment that preceded the weighted average. A borrower deciding whether to consolidate today is therefore not only choosing between a blended count and an intact one; they are choosing which number they will have to defend if their tracker changes. A review of the past month of borrower discussion found the r/PSLF threads of October 2026 dominated by exactly that: trackers frozen since June, counts revised without explanation, and Buyback requests pending since the spring of 2025.
None of this changes the arithmetic in the first table, which is set by regulation and will produce the same blended count whoever administers it. It does change the advice. Certify employment before consolidating so the pre-consolidation count is on record, download the payment history from the servicer, and run the mix through the calculator below with the real balances. If the blended count is close to the unblended one, the plan consequences of the July 2026 cutover are the larger cost; if it is not, the seasoned loan may be better left alone.
PSLF Weighted-Average Calculator: Test Your Own Loan Mix
Methodology
Sources. The Department of Education’s final rule published at 91 FR 23769 (May 1, 2026), the PSLF regulation at 34 CFR 685.219, Federal Student Aid’s pages on studentaid.gov, the Department’s court status reports in AFT v. Department of Education, and explanations from The College Investor, Tate Law, NASFAA and the Student Borrower Protection Center.
How the figures were checked. Every rule and number was compared against its source in early November 2026; figures in court PDFs and the Federal Register were confirmed in the documents themselves. The worked loan mixes apply the official weighted-average formula to example balances; the one scenario we built ourselves is labelled as our calculation.
Limitations. The regulation does not say how a fractional count is rounded, so results are shown unrounded. The September 1, 2024 start of the weighted-average rule is cited from The College Investor; confirm it on studentaid.gov. Your servicer’s count is the one that governs, and the calculator is arithmetic, not a Department determination.
Frequently Asked Questions
Does consolidating reset my PSLF payment count to zero?
Not for Direct Loans. Under 34 CFR 685.219(c)(3) the new Direct Consolidation Loan is credited with the weighted average of the qualifying payments on the Direct Loans it repaid. In Federal Student Aid's example, 60 payments on a $30,000 loan blended with a $30,000 loan at zero become 30. Payments on FFEL or Perkins loans are not Direct Loan payments and add nothing to the average. (Federal Student Aid (studentaid.gov), 2026)
When does consolidation cost me no PSLF payments at all?
When every Direct Loan going into the consolidation carries the same count. A $20,000 loan at 72 payments and a $45,000 loan at 72 payments average to 72, whatever the balances. The loss comes only from mixing a seasoned loan with a loan that has fewer payments, and it scales with that loan's share of the total balance. (Calculated from 34 CFR 685.219(c)(3), 2026)
What changed for consolidations on or after July 1, 2026?
The loan itself is new, and under 34 CFR 685.220(h)(2) a Direct Consolidation Loan made on or after July 1, 2026 may be repaid only under the Tiered Standard plan or the Repayment Assistance Plan. IBR, ICR, PAYE and SAVE are off the table for that loan, and only RAP payments on it can count toward PSLF because the Tiered Standard plan is not PSLF-qualifying. (Federal Register, 91 FR 23769, 2026)
Can I buy back months from before my consolidation?
No. PSLF Buyback can only buy back months on the consolidation loan itself, reaching no further back than the new loan's first disbursement, and it requires 120 months of certified qualifying employment first. Months spent in deferment or forbearance while enrolled in RAP are also not eligible for reconsideration credit under the 2026 final rule. (Tate Law (updated Oct. 23, 2026), 2026)
How is the weighted average rounded?
For PSLF, the regulation does not say. Tate Law's calculator shows an unrounded 58.73 for a $40,000 loan at 116 payments blended with a $39,000 loan at zero and notes that ED publishes no rounding rule. The separate IBR-forgiveness paragraph (34 CFR 685.209(k)(4)(vi)(B)) does round the weighted average up to the nearest whole month. (Tate Law PSLF Weighted Average Calculator, 2026)
How big is the PSLF Buyback backlog right now?
The Department's court-ordered status report put pending Buyback applications at 88,000 on April 30, 2026, a figure it said included roughly 18,000-19,000 duplicates, with 6,600 approvals processed that month. Protect Borrowers' October 30, 2026 lawsuit release says the backlog had grown from 49,000 a year earlier, and Tate Law reports about 82,000 pending as of October 2026. (U.S. Department of Education status report (ECF 65, May 19, 2026), 2026)
Why are borrowers suing over PSLF counts?
Weingarten v. McMahon, filed October 30, 2026 in the U.S. District Court for the District of Columbia, alleges that in August 2026 some borrowers saw PSLF counts drop by 15 months or more after earlier waiver and account-adjustment credits were rolled back, that recent qualifying payments were withheld, and that Buyback applications were left pending without communication. (Protect Borrowers (Oct. 30, 2026), 2026)
Sources & References
- Federal Student Aid. “SAVE Plan Borrowers: FAQs About Choosing a Different Repayment Plan.” studentaid.gov/articles/save/. Accessed 2026-11-07.
- Federal Register. “Reimagining and Improving Student Education — Federal Student Loan Program Final Regulations, 91 FR 23769.” govinfo.gov/content/pkg/FR-2026-05-01/html/2026-08556.htm. Accessed 2026-11-07.
- Federal Register. “Reimagining and Improving Student Education — Final Regulations (document page).” federalregister.gov/documents/2026/05/01/2026-08556/reimagining-and-improving-st. Accessed 2026-11-07.
- Tate Law. “PSLF Weighted Average Payment Count Calculator.” tateesq.com/calculator/pslf-weighted-average-payment-count. Accessed 2026-11-07.
- Tate Law. “PSLF Buyback Program: How It Works and How to Apply.” tateesq.com/learn/pslf-buyback. Accessed 2026-11-07.
- The College Investor. “PSLF Weighted Average Rule Explained.” thecollegeinvestor.com/65178/pslf-weighted-average-rule/. Accessed 2026-11-07.
- U.S. Department of Education. “Status Report, American Federation of Teachers v. U.S. Department of Education, No. 1:25-cv-802 (D.D.C.), ECF 65.” storage.courtlistener.com/recap/gov.uscourts.dcd.278527/gov.uscourts.dcd.278527.. Accessed 2026-11-07.
- Protect Borrowers. “Weingarten v. McMahon: Major Class Action Lawsuit Launched.” protectborrowers.org/weingarten-v-mcmahon/. Accessed 2026-11-07.
- NASFAA. “Biden Administration Extends Loan Consolidation Deadline to Get Credit for Loan Forgiveness.” nasfaa.org/news-item/33682/Biden_Administration_Extends_Loan_Consolidation_Deadl. Accessed 2026-11-07.
Last updated:
This article is general information for U.S. student loan borrowers, not financial or legal advice. Confirm details with your loan servicer or studentaid.gov before acting. See our editorial policy and disclaimer.