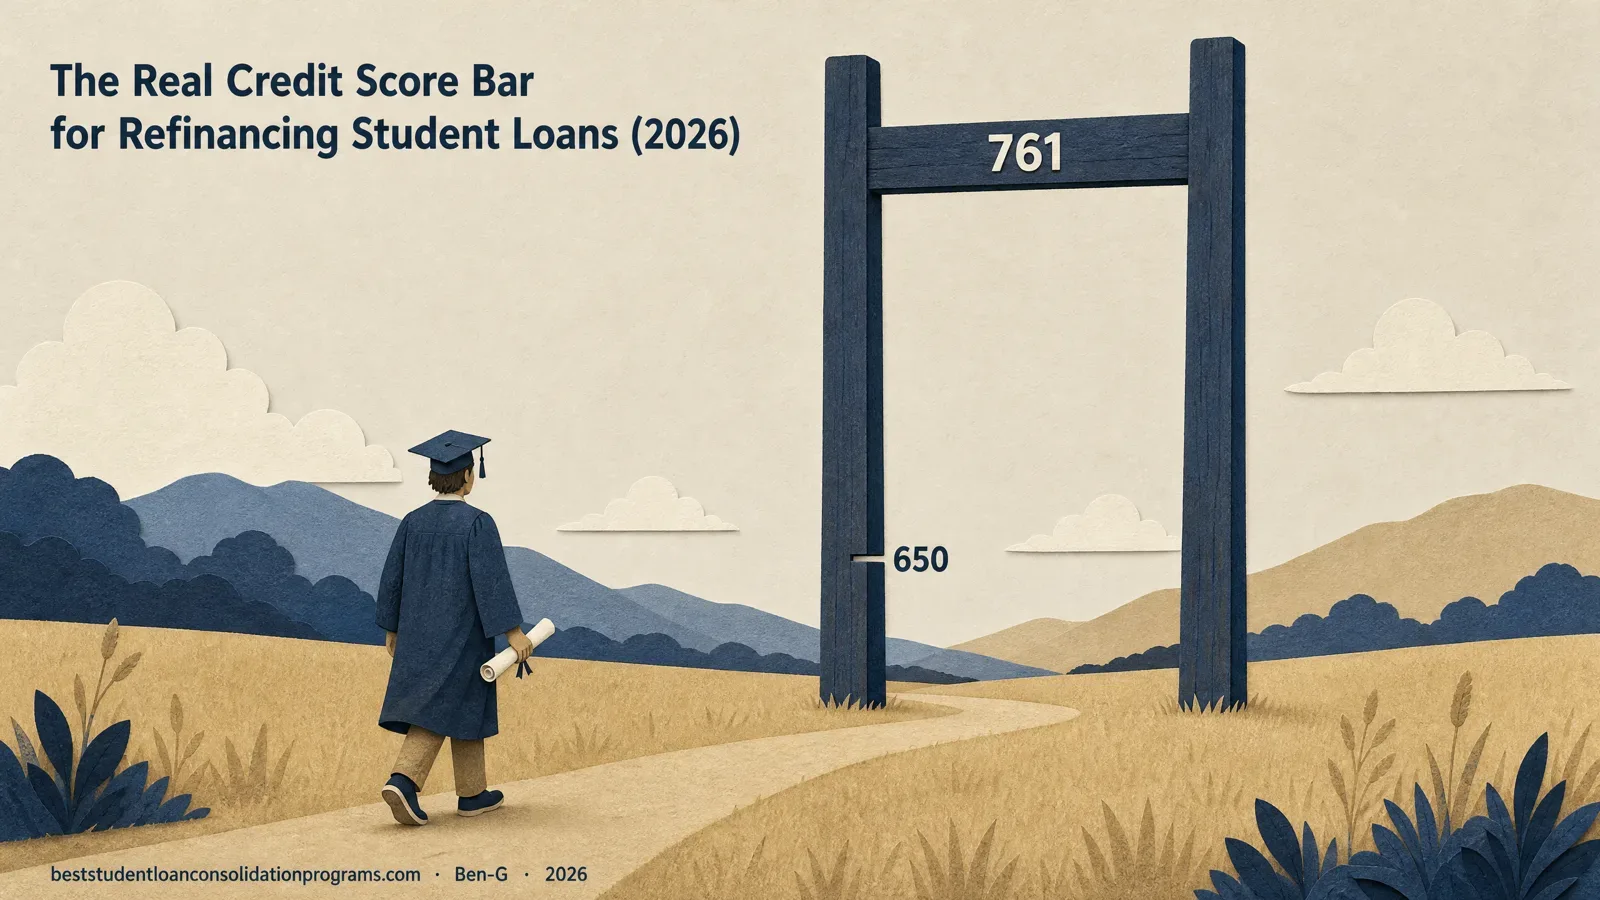
What credit score to refinance student loans do lenders actually approve? The published minimum and the approved average are two different numbers, and this page sources both.
KEY TAKEAWAYS
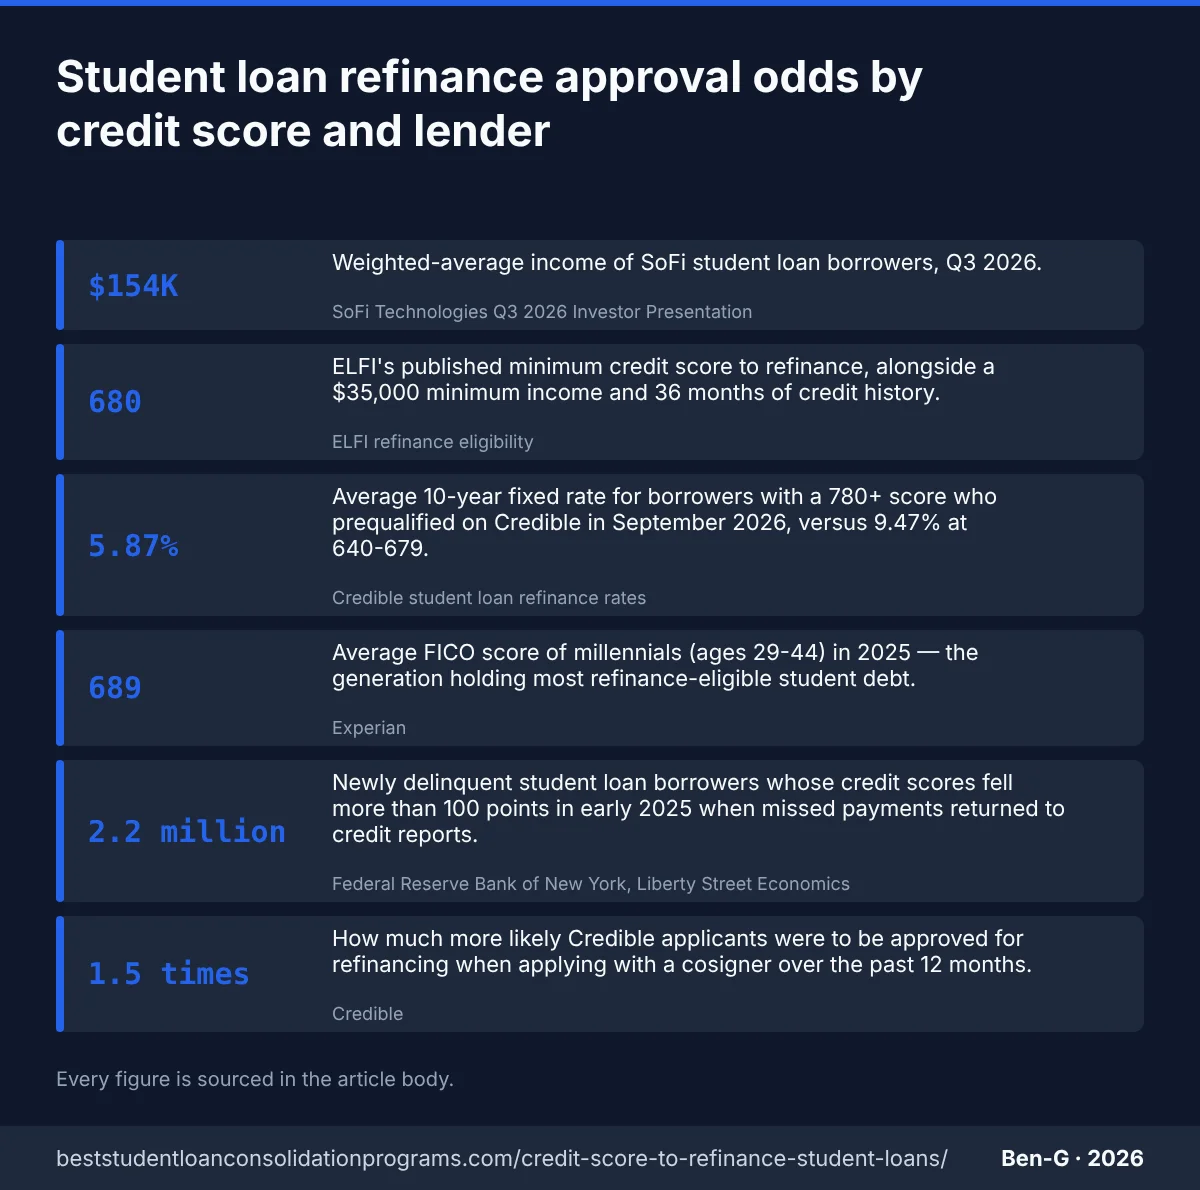
- → $154K Weighted-average income of SoFi student loan borrowers, Q3 2026. (SoFi Technologies Q3 2026 Investor Presentation, 2026)
- → 680 ELFI's published minimum credit score to refinance, alongside a $35,000 minimum income and 36 months of credit history. (ELFI refinance eligibility, 2026)
- → 5.87% Average 10-year fixed rate for borrowers with a 780+ score who prequalified on Credible in September 2026, versus 9.47% at 640-679. (Credible student loan refinance rates, 2026)
- → 689 Average FICO score of millennials (ages 29-44) in 2025 — the generation holding most refinance-eligible student debt. (Experian, 2025)
- → 2.2 million Newly delinquent student loan borrowers whose credit scores fell more than 100 points in early 2025 when missed payments returned to credit reports. (Federal Reserve Bank of New York, Liberty Street Economics, 2025)
- → 1.5 times How much more likely Credible applicants were to be approved for refinancing when applying with a cosigner over the past 12 months. (Credible, 2026)
Ask any lender what credit score to refinance student loans it requires and you get the lowest number it will accept. None of them tells you the score at which it actually says yes. That silence is the gap this page fills. The only major lender that discloses who it approves is SoFi, and its student loan borrowers carried a weighted-average FICO of 761 with a weighted-average income of $154K in the third quarter of this year (SoFi Technologies Q3 2026 Investor Presentation, 2026). The published minimums, meanwhile, cluster between 650 (commonly cited; no primary source traceable) and 720. The distance between those two numbers is the whole story of approval odds, and it is larger than any lender’s marketing page admits.
This matters more now than it did two years ago. When missed federal payments returned to credit reports in early 2025, the New York Fed counted 2.2 million newly delinquent borrowers whose scores fell by more than a hundred points (Federal Reserve Bank of New York, Liberty Street Economics, 2025), and by mid-2026 more than a tenth of all student loan balances were seriously delinquent. A large share of the people searching for a refinance today are doing so from a score that no longer clears any lender’s floor. Below, each data section pairs a published minimum with the evidence of where approvals really land, so you can judge your odds before you spend a hard inquiry.
A note on what this page can and cannot do: it reports disclosed figures only. Lenders do not publish approval rates by credit band, and the securitization reports that carry pool-level FICO and income data sit behind rating-agency paywalls. Where a number is an aggregator’s restatement of a lender’s rule rather than the lender’s own page, the source column says so.
1 What Does an Approved Refinance Borrower Actually Look Like? A 761 FICO and $154K Income
SoFi, the largest refinance originator to disclose a borrower profile, reported a weighted-average FICO of 761 and weighted-average income of $154K for its student loan book in the third quarter of this year, on $2.9 billion of originations, with charge-offs at 63 basis points (SoFi Technologies Q3 2026 Investor Presentation, 2026).
| METRIC | VALUE | SOURCE |
|---|---|---|
| SoFi student loans, weighted-average FICO, Q3 2026 | 761 | SoFi Technologies Q3 2026 Investor Presentation |
| SoFi student loans, weighted-average income, Q3 2026 | $154K | SoFi Technologies Q3 2026 Investor Presentation |
| SoFi student loans, weighted-average FICO, Q4 2025 | 765 | SoFi Technologies Q4 2025 Investor Presentation |
| SoFi student loans, weighted-average income, Q4 2025 | $149K | SoFi Technologies Q4 2025 Investor Presentation |
| SoFi personal loans, weighted-average FICO, Q3 2026 (comparison) | 743 | SoFi Technologies Q3 2026 Investor Presentation |
| SoFi student loan originations, Q3 2026 | $2.9 billion | SoFi Technologies Q3 2026 earnings release (SEC 8-K) |
| SoFi student loan annualized charge-off rate, Q3 2026 | 63 basis points | SoFi Technologies Q3 2026 earnings release (SEC 8-K) |
| SoFi average student loan balance, Q3 2026 | $44,113 | SoFi Technologies Q3 2026 earnings release (SEC 8-K) |
Two things stand out in SoFi’s disclosure. First, the approved student loan book is more creditworthy than the company’s own personal loan book: 761 against 743 on FICO, on almost identical income. Refinancing is underwritten as a prime product, and the growth is coming from the prime end. Originations of $2.9 billion in a single quarter were the highest in the company’s history, and the charge-off rate of 63 basis points is what a book built around a 760 average produces. The borrowers being added are not lowering the bar; they are raising it.
Second, the profile is stable. A year earlier the same table showed 765 and $149K (SoFi Technologies Q4 2025 Investor Presentation, 2025). Rates moved, volume doubled, and the typical approved borrower barely changed. That is the strongest evidence this page has that the approved profile is a policy, not an accident of who applied. For a borrower reading the lender’s eligibility page, which lists no minimum score at all (SoFi eligibility requirements, 2026), the useful number is not the floor but the center of gravity: a score in the mid-700s and income well into six figures. If you are comparing programs on our student loan consolidation guide, treat this profile as the benchmark every undisclosed lender is likely pricing against.
2 What Credit Score to Refinance Student Loans Does Each Lender Publish?
Published minimums run from 650 at Earnest to 720 at Brazos, with ELFI at 680 plus a $35,000 income floor (ELFI refinance eligibility, 2026). SoFi and Laurel Road publish no minimum at all; the typical base lenders require is about 670, per Experian (CNBC Select, 2026).
| LENDER | PUBLISHED MINIMUM | SOURCE |
|---|---|---|
| ELFI (plus minimum income below) | 680 | ELFI refinance eligibility |
| ELFI minimum income | $35,000 | ELFI refinance eligibility |
| Earnest (aggregators disagree: see note) | 650 | NerdWallet, Earnest vs. SoFi (updated Oct 15, 2026) |
| LendKey | 680 | Credible lender table (updated Nov 6, 2026) |
| MEFA | 670 | Credible lender table (updated Nov 6, 2026) |
| EdvestinU | 700 | Credible lender table (updated Nov 6, 2026) |
| Splash Financial (soft minimum) | 700 | educationdata.org lender comparison (updated Oct 7, 2026) |
| Brazos (without cosigner) | 720 | Credible lender table (updated Nov 6, 2026) |
| SoFi | none disclosed | SoFi eligibility requirements |
| Laurel Road (KeyBank) | none disclosed | KeyBank / Laurel Road student loan refinancing |
| Typical base requirement (Experian, via CNBC) | 670 | CNBC Select |
| Credible marketplace fixed APR range, Nov 2026 | 3.95% to 11.99% | Credible student loan refinance rates |
| ELFI lowest fixed APR, late Oct 2026 | 4.49% | ELFI refinance eligibility |
The table splits into three groups. ELFI is the transparent case: a 680 score, $35,000 in income, three years of credit history and a bachelor’s degree, all printed on its own page. The credit-union and state-agency lenders (LendKey, MEFA, EdvestinU, Brazos) publish floors that aggregators can restate, though the restatements drift: Credible lists Earnest at a different figure than NerdWallet does, which is why Earnest’s 650 is flagged as contested here. Then there are the two largest brands, SoFi and Laurel Road, which publish nothing. SoFi’s page says eligibility rests on financial history, credit score and monthly income versus expenses (SoFi eligibility requirements, 2026); KeyBank’s says credit profile, monthly income and monthly debt payments (KeyBank / Laurel Road student loan refinancing, 2026).
Read together with the previous section, the pattern is uncomfortable but clear. The lender with no published minimum has the most selective disclosed book. A borrower at 670, which Experian describes as the usual base, is roughly ninety points below where SoFi’s approvals cluster. Whether a score at the floor converts to an approval depends on the variables none of these pages quantify: income, debt-to-income, degree and employment. The minimum is the price of admission to underwriting, not a probability of leaving with a loan.
3 How Much Does Each Credit Band Cost in Rate? From 5.87% to 9.68%
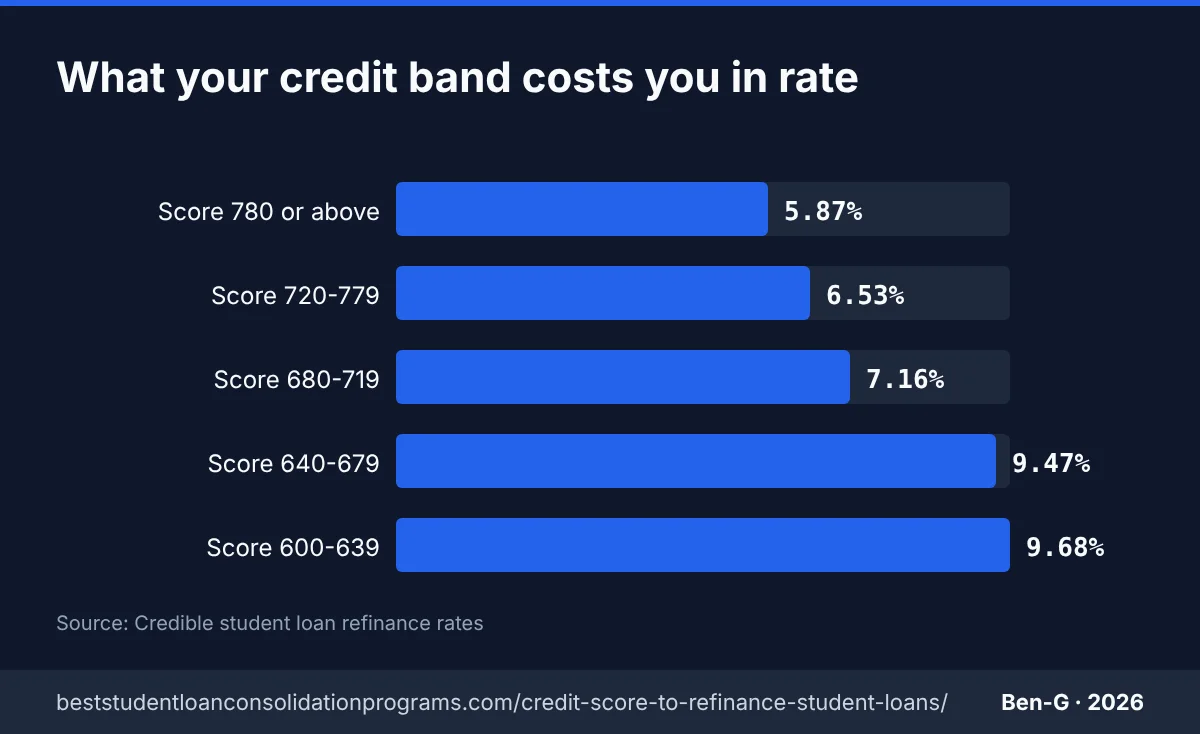
Borrowers who prequalified on Credible in September averaged 5.87% on ten-year fixed loans with a score of 780 or above, 6.53% at 720-779, 7.16% at 680-719, and 9.47% at 640-679 (Credible student loan refinance rates, 2026). The largest single step is the drop below 680, worth more than two percentage points.
| CREDIT BAND (10-YEAR FIXED, CREDIBLE PREQUALIFIED, SEPT 2026) | AVERAGE RATE | SOURCE |
|---|---|---|
| 780 or above | 5.87% | Credible student loan refinance rates |
| 720 to 779 | 6.53% | Credible student loan refinance rates |
| 680 to 719 | 7.16% | Credible student loan refinance rates |
| 640 to 679 | 9.47% | Credible student loan refinance rates |
| 600 to 639 | 9.68% | Credible student loan refinance rates |
These are averages for people who prequalified, so they already exclude the applicants a lender turned away at the soft-pull stage. That makes the shape of the curve more telling, not less. Between the top band and the 720-779 band the penalty is modest; between 680-719 and 640-679 it is a cliff. The step from 7.16% to 9.47% is the market telling you where its appetite ends. Below 680, a refinance is priced like a fair-credit personal loan, and for a borrower with federal loans it will rarely beat the fixed rate they already hold.
The band table also answers the question running through r/StudentLoans this autumn, where borrowers asked whether anyone could still refinance private loans below roughly four and three-quarters percent. The marketplace’s lowest advertised fixed rate is 3.95% to 11.99% at the bottom of the range, and ELFI’s best fixed rate was 4.49% in late October. Those floors are reserved for the top band, with autopay, usually on the shortest terms. For a 720-779 borrower the realistic ten-year number is 6.53%, and planning around the advertised floor is the most common reason a refinance disappoints.
4 Where Do Student Loan Borrowers Actually Stand? Average Millennial FICO Is 689
The average U.S. FICO score was 713 in 2025, but millennials averaged 689 and Gen Z 678 (Experian, 2025). Only about half of all consumers score 740 or above (27.5% very good plus 22.8% exceptional), the zone where SoFi’s disclosed approvals sit.
| METRIC | VALUE | SOURCE |
|---|---|---|
| Average U.S. FICO score, 2025 | 713 | Experian |
| Average FICO, millennials (29-44) | 689 | Experian |
| Average FICO, Generation Z (18-28) | 678 | Experian |
| Share of consumers 740-799 (very good) | 27.5% | Experian |
| Share of consumers 800-850 (exceptional) | 22.8% | Experian |
| Share of consumers 670-739 (good) | 20.1% | Experian |
| Share of consumers 580-669 (fair) | 14.9% | Experian |
| Share of consumers 300-579 (poor) | 14.7% | Experian |
Student debt is concentrated in the two youngest generations, and those are the two with the lowest average scores. A millennial at the generational average of 689 clears Earnest’s 650 floor and ELFI’s 680, and would price into the 680-719 band at 7.16%. A Gen Z borrower at 678 is above the Experian base of 670 by a handful of points and one late payment away from falling under it. Neither is near the 761 center of SoFi’s approved book.
The distribution explains the Reddit threads where a borrower with a score in the high 700s is still declined. Roughly half the adult population is in the 740-plus zone, so a lender aiming at a 760 average is not short of applicants who clear the score test; it can afford to decline on income, debt-to-income or employment. Score gets you into the pool. The other variables, which no lender publishes as thresholds, decide who comes out.
5 How Did the 2025 Credit-Score Crash Change Who Can Refinance? 2.2 Million Borrowers Lost 100+ Points
When missed federal payments returned to credit reports, the New York Fed found 2.2 million newly delinquent borrowers lost more than a hundred points; those previously above 720 saw an average change of -177 points (Federal Reserve Bank of New York, Liberty Street Economics, 2025). By the second quarter of this year, 10.6% of student loan balances were ninety-plus days delinquent (Federal Reserve Bank of New York, Quarterly Report on Household Debt and Credit, Q2 2026, 2026).
| METRIC | VALUE | SOURCE |
|---|---|---|
| Newly delinquent borrowers with score drops over 100 points, Q1 2025 | 2.2 million | Federal Reserve Bank of New York, Liberty Street Economics |
| Average score change, newly delinquent borrowers previously above 720 | -177 | Federal Reserve Bank of New York, Liberty Street Economics |
| Average score change, newly delinquent borrowers at 620-719 | -140 | Federal Reserve Bank of New York, Liberty Street Economics |
| Newly delinquent borrowers who had scores above 620 | 2.4 million | Federal Reserve Bank of New York, Liberty Street Economics |
| Borrowers with a payment due who were behind, Q1 2025 | 23.7% | Federal Reserve Bank of New York, Liberty Street Economics |
| Student loan balances 90+ days delinquent, Q2 2026 | 10.6% | Federal Reserve Bank of New York, Quarterly Report on Household Debt and Credit, Q2 2026 |
| Outstanding U.S. student loan debt, Q2 2026 | $1.65 trillion | Federal Reserve Bank of New York, Quarterly Report on Household Debt and Credit, Q2 2026 |
No lender page and no comparison site puts these two datasets side by side, which is why this section exists. The New York Fed’s numbers describe a shock that landed hardest on the borrowers refinance lenders most want. Of the newly delinquent, 2.4 million had scores above 620 before the missed payment, and the ones above 720 saw an average change of -177 points. A 760 becomes a 583. That is not a borrower who prices into a worse band; that is a borrower who is out of the market entirely, and a delinquency on the report blocks approval at most lenders regardless of the recovered score.
The scale is not small. Nearly a quarter of borrowers with a payment due were behind in the first quarter of 2025 (23.7%), and the serious-delinquency share of balances stood at 10.6% a year later on $1.65 trillion of outstanding debt. The practical reading for anyone who missed payments during the transition: the refinance market has not loosened to meet you. SoFi’s approved average moved from 765 to 761 over the same period, a rounding error. The borrowers who can refinance are, if anything, a narrower slice of the population than before the delinquency reporting restarted.
6 What Does Applying Cost Your Score, and Who Is Approving More in 2026?
One additional hard inquiry costs most people less than 5 points, affects the score for 1 year, and FICO ignores student loan inquiries made within 30 days of scoring (myFICO, 2026). Applicants with a cosigner were 1.5 times as likely to be approved on Credible (Credible, 2026), while Navient’s Earnest refinance originations reached $735 million in a single quarter.
| METRIC | VALUE | SOURCE |
|---|---|---|
| FICO impact of one additional hard inquiry (most people) | less than 5 points | myFICO |
| How long a hard inquiry affects FICO scores | 1 year | myFICO |
| Student loan rate-shopping buffer (inquiries ignored if within) | 30 days | myFICO |
| Weight of new credit, including inquiries, in a FICO score | 10% | myFICO |
| Approval odds with a cosigner vs without (Credible, last 12 months) | 1.5 times | Credible |
| Navient (Earnest) refinance originations, Q2 2026 | $735 million | Navient Q2 2026 earnings release |
| Navient (Earnest) refinance originations, Q1 2026 | $778 million | Navient Q1 2026 earnings presentation |
| Credible refinance volume, last year | $700 million | Credible student loan refinance rates |
The fear of the hard pull is overstated. FICO’s own guidance is that an extra inquiry costs less than 5 points, counts for 1 year, and that inquiries carry 10% of the score’s weight. Student loan applications made within 30 days are ignored at scoring time, and older ones in a shopping window are treated as one. The right sequence is soft-pull prequalification across several lenders first, then a single cluster of full applications. What damages approval odds is not the inquiry; it is applying at a score that was never going to clear the real bar and then waiting a year to try again.
The supply side is expanding, but at the prime end. Navient’s Earnest brand originated $778 million in the first quarter and $735 million in the second, both up by roughly two-thirds on the prior year, and the company says its refinance borrowers’ average FICO rose three points over that period without disclosing the level (Navient Q1 2026 earnings presentation, 2026). Credible moved $700 million through its marketplace last year. More money is chasing the same 740-plus borrower. For everyone else, the measurable lever is a cosigner: Credible’s applicants with one were 1.5 times as likely to be approved, and lenders such as Brazos cut their published minimum by thirty points when a cosigner signs. That is the closest thing to a published approval rate the industry offers.
Explore every figure in this article
Methodology
Sources. SoFi Technologies’ Q3 2026 and Q4 2025 investor presentations and its Q3 2026 earnings release filed with the SEC; the eligibility pages of ELFI, SoFi and KeyBank (Laurel Road); Credible’s rate-by-score table and lender table; Experian’s 2025 score distribution; the Federal Reserve Bank of New York’s Liberty Street Economics analysis and its Q2 2026 Household Debt and Credit report; myFICO; and Navient’s 2026 earnings releases.
How the figures were checked. Every number was compared against the page or document it comes from in early November 2026. Figures inside PDFs (investor decks, the New York Fed report, Navient’s releases) were confirmed by opening the document itself.
Limitations. Lenders do not publish approval rates by credit score, and the securitization reports that carry pool-level FICO and income data are sold by rating agencies, so this page cannot give a cross-lender approved average. SoFi’s disclosure is the only approved-borrower profile available. Lender minimums restated by comparison sites (Credible, NerdWallet, educationdata.org) rather than the lender itself are marked as such, and Earnest’s minimum, which those sites report differently, is marked as disputed.
Frequently Asked Questions
What credit score do you need to refinance student loans in 2026?
Published minimums run from 650 (Earnest) to 720 (Brazos), with ELFI at 680 and LendKey at 680 per Credible's November 2026 lender table; SoFi and Laurel Road publish none. But the only disclosed approved-borrower profile, SoFi's, shows a weighted-average FICO of 761 in Q3 2026 — the minimum is where applications are accepted, not where most approvals happen. (Credible lender table; SoFi Q3 2026 Investor Presentation, 2026)
Why was I denied a student loan refinance with a 750+ credit score?
Lenders underwrite income and debt load, not just the score. SoFi's eligibility page weighs 'monthly income vs. expenses' and requires employment; Laurel Road cites 'monthly debt payments'. SoFi's approved student loan borrowers averaged $154,000 in income in Q3 2026, so a high score with thin or variable income can still be declined. (SoFi eligibility requirements, 2026)
How much does a lower credit score raise my refinance rate?
On Credible in September 2026, borrowers with a 780+ score prequalified at an average 5.87% on 10-year fixed loans; 720-779 averaged 6.53%, 680-719 averaged 7.16%, and 640-679 jumped to 9.47%. The biggest step is crossing below 680, where the average rate rises by more than two percentage points. (Credible student loan refinance rates, 2026)
Does the average student loan borrower meet the lenders' bar?
Not comfortably. Experian puts the 2025 average FICO at 713 overall, 689 for millennials and 678 for Gen Z. About half of all consumers score 740 or above (27.5% very good plus 22.8% exceptional), which is roughly where SoFi's disclosed approved book (761) sits. (Experian, 2025)
Did missed federal payments in 2025 hurt refinance eligibility?
Yes, for millions. The New York Fed found more than 2.2 million newly delinquent student loan borrowers lost over 100 points in early 2025; those who had scored above 720 dropped an average of 177 points. By Q2 2026, 10.6% of student loan balances were 90+ days delinquent. A delinquency on file blocks refinancing at most lenders regardless of the current score. (Federal Reserve Bank of New York, 2025)
Will applying to several refinance lenders damage my credit score?
Barely, if you cluster the applications. myFICO says one additional hard inquiry costs most people less than five points, inquiries affect the score for only a year, and FICO ignores student loan inquiries made in the 30 days before scoring. Prequalification with a soft pull, which Credible and most lenders offer, costs nothing. (myFICO, 2026)
Does a cosigner really improve approval odds?
Credible reports that applicants over the past 12 months were more than 1.5 times as likely to be approved when they applied with a cosigner. Several lenders also lower their minimum with one: Brazos lists 720 alone versus 690 with a cosigner, per educationdata.org's October 2026 comparison. (Credible, 2026)
Sources & References
- SoFi Technologies. “Q3 2026 Investor Presentation.” s27.q4cdn.com/749715820/files/doc_financials/2026/q3/2026-Q3-Investor-Presentati. Accessed 2026-11-07.
- SoFi Technologies. “Q4 2025 Investor Presentation.” s27.q4cdn.com/749715820/files/doc_financials/2025/q4/2025-Q4-Investor-Presentati. Accessed 2026-11-07.
- SoFi Technologies. “Third Quarter 2026 earnings release (Form 8-K exhibit).” sec.gov/Archives/edgar/data/0001818874/000181887426000065/a2026q3earningsrelease. Accessed 2026-11-07.
- SoFi. “Eligibility requirements.” sofi.com/eligibility/. Accessed 2026-11-07.
- ELFI. “Refinance Student Loans — eligibility FAQ.” elfi.com/refinance-student-loans/. Accessed 2026-11-07.
- KeyBank / Laurel Road. “Student Loan Refinancing.” key.com/personal/student-loans/student-loan-refinancing.html. Accessed 2026-11-07.
- NerdWallet. “Earnest vs. SoFi: Which Is Better for Refinancing Student Loans?.” nerdwallet.com/student-loans/learn/earnest-vs-sofi-refinancing. Accessed 2026-11-07.
- Credible. “Best Student Loan Refinance Rates in November 2026.” credible.com/refinance-student-loans. Accessed 2026-11-07.
- Credible. “Best Student Loans for Refinancing Without a Cosigner.” credible.com/refinance-student-loans/refinance-without-cosigner. Accessed 2026-11-07.
- educationdata.org. “Refinance Student Loans: 35+ Lenders Compared.” educationdata.org/student-loan-refinancing. Accessed 2026-11-07.
- CNBC Select. “Student Loan Refinancing: How To Get Approved.” cnbc.com/select/average-credit-score-needed-to-refinance-student-loans/. Accessed 2026-11-07.
- Experian. “What Is the Average Credit Score in the U.S.?.” experian.com/blogs/ask-experian/what-is-the-average-credit-score-in-the-u-s/. Accessed 2026-11-07.
- Federal Reserve Bank of New York. “Student Loan Delinquencies Are Back, and Credit Scores Take a Tumble.” libertystreeteconomics.newyorkfed.org/2025/05/student-loan-delinquencies-are-bac. Accessed 2026-11-07.
- Federal Reserve Bank of New York. “Quarterly Report on Household Debt and Credit, 2026:Q2.” newyorkfed.org/medialibrary/interactives/householdcredit/data/pdf/hhdc_2026q2.pd. Accessed 2026-11-07.
- myFICO. “Credit Checks: What are credit inquiries and how do they affect your FICO Score?.” myfico.com/credit-education/credit-reports/credit-checks-and-inquiries. Accessed 2026-11-07.
- Navient. “Second Quarter 2026 Earnings Release.” images.navient.com/Investors/shareholder/NAVI_2Q-26_Earnings_Release_8.6.26.pdf. Accessed 2026-11-07.
- Navient. “First Quarter 2026 Earnings Call Presentation.” images.navient.com/Investors/shareholder/NAVI_Earnings_Presentation_1q2026.pdf. Accessed 2026-11-07.
Last updated:
This article is general information for U.S. student loan borrowers, not financial or legal advice. Confirm details with your loan servicer or studentaid.gov before acting. See our editorial policy and disclaimer.