Student Loan Consolidation Cost: The Three Charges Priced in Dollars (2026)
KEY TAKEAWAYS
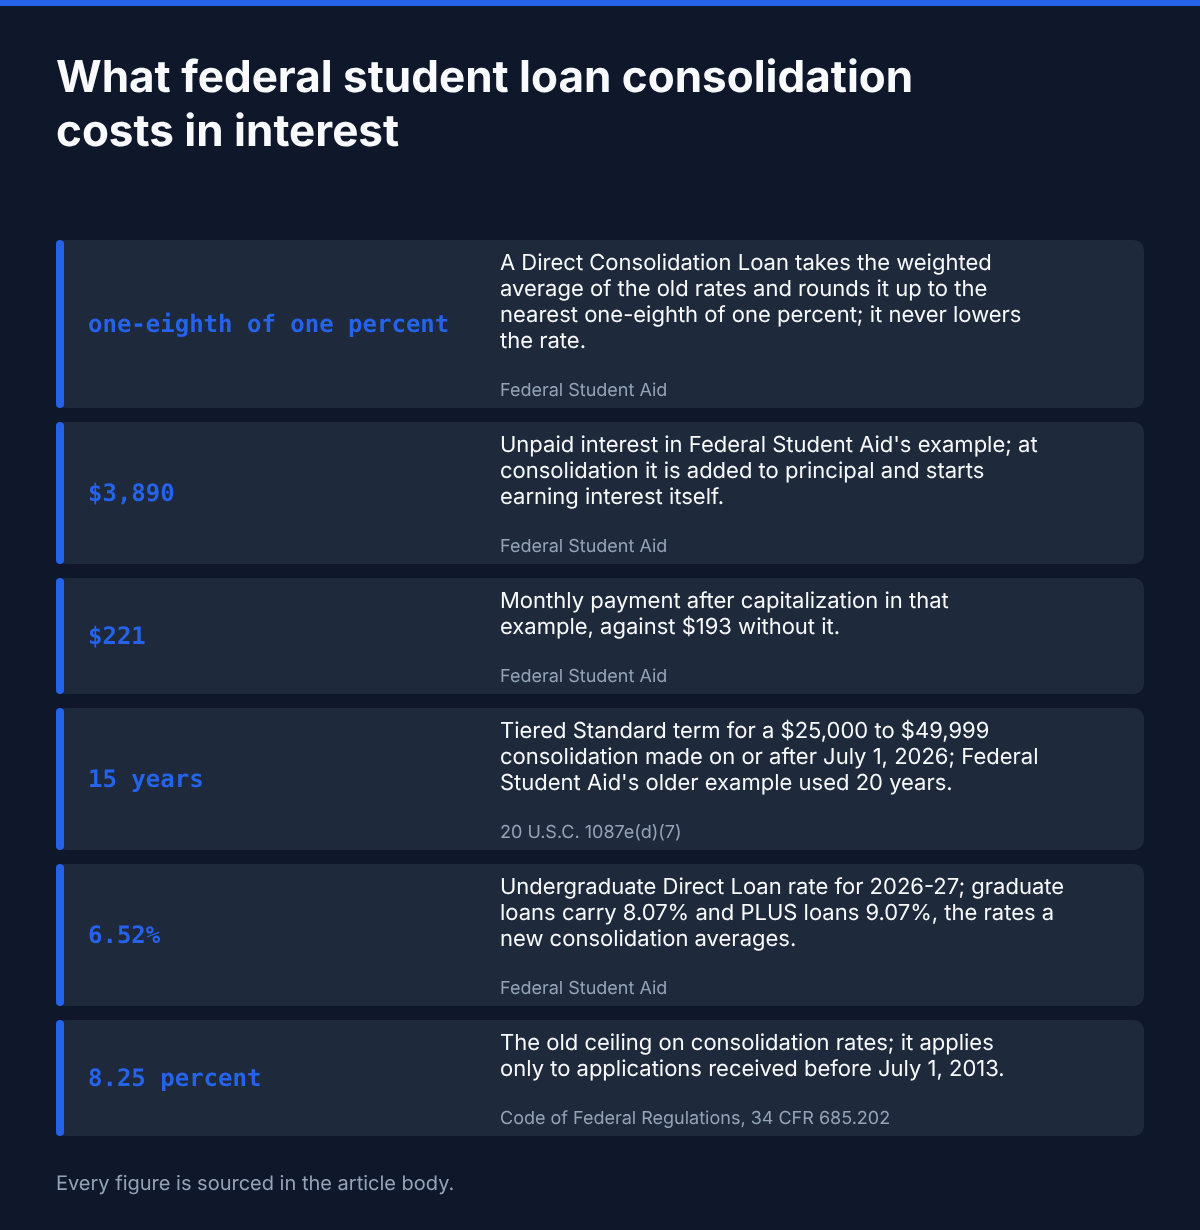
- → one-eighth of one percent A Direct Consolidation Loan takes the weighted average of the old rates and rounds it up to the nearest one-eighth of one percent; it never lowers the rate. (Federal Student Aid, 2026)
- → $3,890 Unpaid interest in Federal Student Aid's example; at consolidation it is added to principal and starts earning interest itself. (Federal Student Aid, 2026)
- → $221 Monthly payment after capitalization in that example, against $193 without it. (Federal Student Aid, 2026)
- → 15 years Tiered Standard term for a $25,000 to $49,999 consolidation made on or after July 1, 2026; Federal Student Aid’s older example used 20 years. (20 U.S.C. 1087e(d)(7), 2026)
- → 6.52% Undergraduate Direct Loan rate for 2026-27; graduate loans carry 8.07% and PLUS loans 9.07%, the rates a new consolidation averages. (Federal Student Aid, 2026)
- → 8.25 percent The old ceiling on consolidation rates; it applies only to applications received before July 1, 2013. (Code of Federal Regulations, 34 CFR 685.202, 2026)
A Direct Consolidation Loan has no application fee, which is why most guides call it free. It is not. Consolidation changes three things about your debt at once, and each one has a price: the rate is rounded up, unpaid interest is folded into principal, and the repayment clock can be stretched. Federal Student Aid’s own worked example shows the middle one alone turning $46,425 into $53,113 (Federal Student Aid, 2026).
Few guides compare the three side by side. Borrowers are warned about the round-up constantly, yet on realistic balances it is the smallest of the three by a wide margin. This page prices each charge separately, using the official example, the regulation and the federal rates now in force, so you can see which ones you can avoid before you sign. It sits alongside our guides in the federal loan consolidation section.
A note on scope before the numbers. Everything here concerns federal Direct Consolidation, the government program that combines federal loans into one federal loan. It is not the same thing as private refinancing, which replaces federal loans with a bank loan at a new rate. The two are confused constantly, and the confusion is expensive, because the first can never reduce your rate and the second can never give your federal protections back. Where a figure is our own arithmetic rather than a quoted number, the table says so, and the method is set out at the end.
1 What Does the 1/8-Point Round-Up Actually Cost? $25 to About $2,570
The consolidation rate is the weighted average of your old rates, rounded up to the nearest one-eighth of one percent (Federal Student Aid, 2026). The bump is therefore always below 0.125 points. On a $27,000 undergraduate mix it adds about $25 over ten years; on $100,000 over 25 years a full 0.125-point bump costs about $2,300 at a 6% blend and about $2,570 at a 9% blend (our calculation).
| METRIC | VALUE | SOURCE |
|---|---|---|
| Rounding rule | one-eighth of one percent | Federal Student Aid |
| Largest possible bump | Just under 0.125 points (calculated) | Federal Student Aid |
| Typical bump across random loan mixes | About 0.06 points (calculated) | Federal Student Aid |
| $27,000 undergraduate mix, 10 years, bump 0.015 | About $25 extra (calculated) | Federal Student Aid |
| $35,000 undergraduate plus graduate mix, 10 years, bump 0.066 | About $143 extra (calculated) | Federal Student Aid |
| $100,000 graduate plus PLUS mix, 20 years (pre-July 2026 terms), bump 0.03 | About $455 extra (calculated) | Federal Student Aid |
| Worst case, $100,000 over 25 years, full 0.125 bump | About $2,300 to $2,570 extra (calculated) | Federal Student Aid |
The round-up is real but small because it is bounded. Whatever your loans are, the new rate lands on the next eighth above your dollar-weighted average, so the penalty depends on luck: a blend of 6.235% rounds to 6.25% and costs almost nothing, while a blend that sits just above an eighth pays nearly the full step. Our worked mixes use the rates on loans issued in recent years, and the weighted-average arithmetic is the same one that governs payment counts.
Two practical points follow. First, the round-up is charged on the whole balance for the whole term, so it grows with both. Second, it cannot be avoided once you consolidate, but it can be checked in advance: the Direct Consolidation Loan application shows the weighted rate before you submit. Borrowers comparing this against a private refinance should read how lenders price credit in our refinance approval data first.
It helps to see why the range is so wide. The bump itself is a fraction of a point, but it is multiplied by the balance and then by time. A borrower with a small balance on a ten-year schedule pays the price of a coffee each month at most. A borrower with six figures of graduate debt on a long schedule pays the same fraction on a far larger base for more than twice as long. The round-up alone is rarely a reason to avoid consolidating, but since July 1, 2026 the plan consequences often are. It is simply a cost to know, and in most cases the smallest line on the bill.
2 How Much Does Capitalized Interest Add? About $2,000 to $2,800 on a $27,000 Loan
When loans are consolidated, any unpaid interest is added to principal. In Federal Student Aid’s example, $3,890 of unpaid interest on a $27,000 loan raises the monthly payment from $193 to $221 and the 20-year total from $46,425 to $53,113 (Federal Student Aid, 2026). The $3,890 is owed either way; what capitalization adds is the interest charged on it: about $2,798 over that 20-year example, or about $2,019 over the 15-year term a $27,000 consolidation gets today (our calculation).
| METRIC | VALUE | SOURCE |
|---|---|---|
| Starting principal | $27,000 | Federal Student Aid |
| Unpaid interest at consolidation | $3,890 | Federal Student Aid |
| Monthly payment, no unpaid interest | $193 | Federal Student Aid |
| Monthly payment after capitalization | $221 | Federal Student Aid |
| 20-year total, no unpaid interest | $46,425 | Federal Student Aid |
| 20-year total after capitalization | $53,113 | Federal Student Aid |
| Interest charged on the capitalized $3,890 | $2,798 over 20 years (FSA example); about $2,019 over 15 years (calculated) | Federal Student Aid |
This is the cost most borrowers can control. Capitalization only bites on interest that is unpaid on the day the consolidation is made, which is common after forbearance, after a default, or straight out of a grace period on unsubsidized loans. Paying the accrued interest before you apply leaves little to capitalize, though some accrues while the application is processed. Borrowers leaving default face a version of the same choice, covered in our comparison of rehabilitation and consolidation.
The damage also compounds with the other two charges. Capitalized interest raises the balance that the rounded-up rate applies to, and a longer term gives that larger balance more years to accrue. For anyone already behind, the default-related articles explain what is added to the balance before consolidation even starts.
The size of the hit is set by how long interest has been allowed to pile up unpaid. A recent graduate consolidating at the end of a grace period typically carries the interest that built up on unsubsidized loans during school. Someone who spent a year or two in forbearance carries far more. In both situations the borrower can ask the servicer for the accrued interest figure and pay it off before submitting the application. That single payment is the cheapest way to cut the cost of a consolidation, because every dollar of interest cleared in advance is a dollar that never becomes principal and never earns interest of its own for the next two decades.
3 What Does Stretching From 10 to 15 Years Cost? About $5,041
A Direct Consolidation Loan made on or after July 1, 2026 can use only the Tiered Standard plan or RAP (20 U.S.C. 1087e(d)(7), (g)(3)). Under Tiered Standard the term depends on the total principal of all your Direct Loans, so a $27,000 balance gets 15 years. Federal Student Aid’s older example, written before that change, used a term of 20 years (Federal Student Aid, 2026). At 6%, a 10-year schedule on $27,000 costs about $35,971 in total and a 15-year schedule about $41,011: the longer term cuts the payment by about $72 a month and adds about $5,041 (our calculation). On the older 20-year term the total was $46,425, about $10,454 more than 10 years.
| METRIC | VALUE | SOURCE | |
|---|---|---|---|
| Term in Federal Student Aid’s pre-July 2026 example | 20 years | Federal Student Aid | |
| 10-year monthly payment on the example loan | About $300 (calculated) | Federal Student Aid | |
| 20-year monthly payment (pre-July 2026 example) | $193 | Federal Student Aid | |
| 10-year total | About $35,971 (calculated) | Federal Student Aid | |
| 20-year total | $46,425 | Federal Student Aid | |
| Extra paid for 20 years vs 10 (pre-July 2026 example) | About $10,454 (calculated) | ||
| 15-year Tiered Standard monthly payment, $27,000 at 6% | About $228 (calculated) | 20 U.S.C. 1087e(d)(7) | |
| 15-year total, and extra vs 10 years | About $41,011; $5,041 more (calculated) | 20 U.S.C. 1087e(d)(7) | Federal Student Aid |
| Tiered Standard term under $25,000 | 10 years | Federal Student Aid | |
| Tiered Standard term at $100,000 or more | 25 years | Federal Student Aid |
Term is where the money is. On the official example the stretch costs more than capitalization and several hundred times more than a typical round-up. It is also the easiest to undo: there is no prepayment penalty on federal loans, so a borrower who consolidates for convenience and keeps paying the old 10-year amount avoids most of the extra interest from the longer schedule, though not the round-up, the capitalization or the loss of older repayment plans.
The rules on term changed this year. For borrowers with any loan disbursed on or after July 1, 2026, the only standard option is the Tiered Standard plan, which sets the term by the total principal of all your Direct Loans: 10 years under $25,000, 15 years from $25,000 to $49,999, 20 years from $50,000 to $99,999 and 25 years at $100,000 or more (Federal Student Aid, 2026). The biggest cost of a consolidation made on or after July 1, 2026 is not in dollars of interest: the new loan, and every other Direct Loan you hold, can then be repaid only under the Repayment Assistance Plan or the Tiered Standard plan, so IBR, PAYE and ICR are gone, and time earned toward income-driven forgiveness may not carry over (20 U.S.C. 1087e(d)(7)). A consolidation that includes a parent PLUS loan gets the Tiered Standard plan only. And for public servants the effect on PSLF payment counts usually matters more than any of the dollar figures here.
The reason this cost is so often missed is that it arrives looking like a benefit. A lower monthly bill is what most people are hoping for when they consolidate, and the application delivers it. The trade is rarely shown in the same place: the same loan, at the same rate, costs about 14 percent more in total over 15 years than over 10, and about 29 percent more over 20 (our calculation). Borrowers who need the lower payment to stay current should take it without guilt, since missed payments cost more than interest does. Borrowers who do not need it should treat the longer term as an option they hold, not a schedule they must follow, and keep paying at the faster pace.
4 Which Rates Does a 2026 Consolidation Average? 2.75% to 9.07%
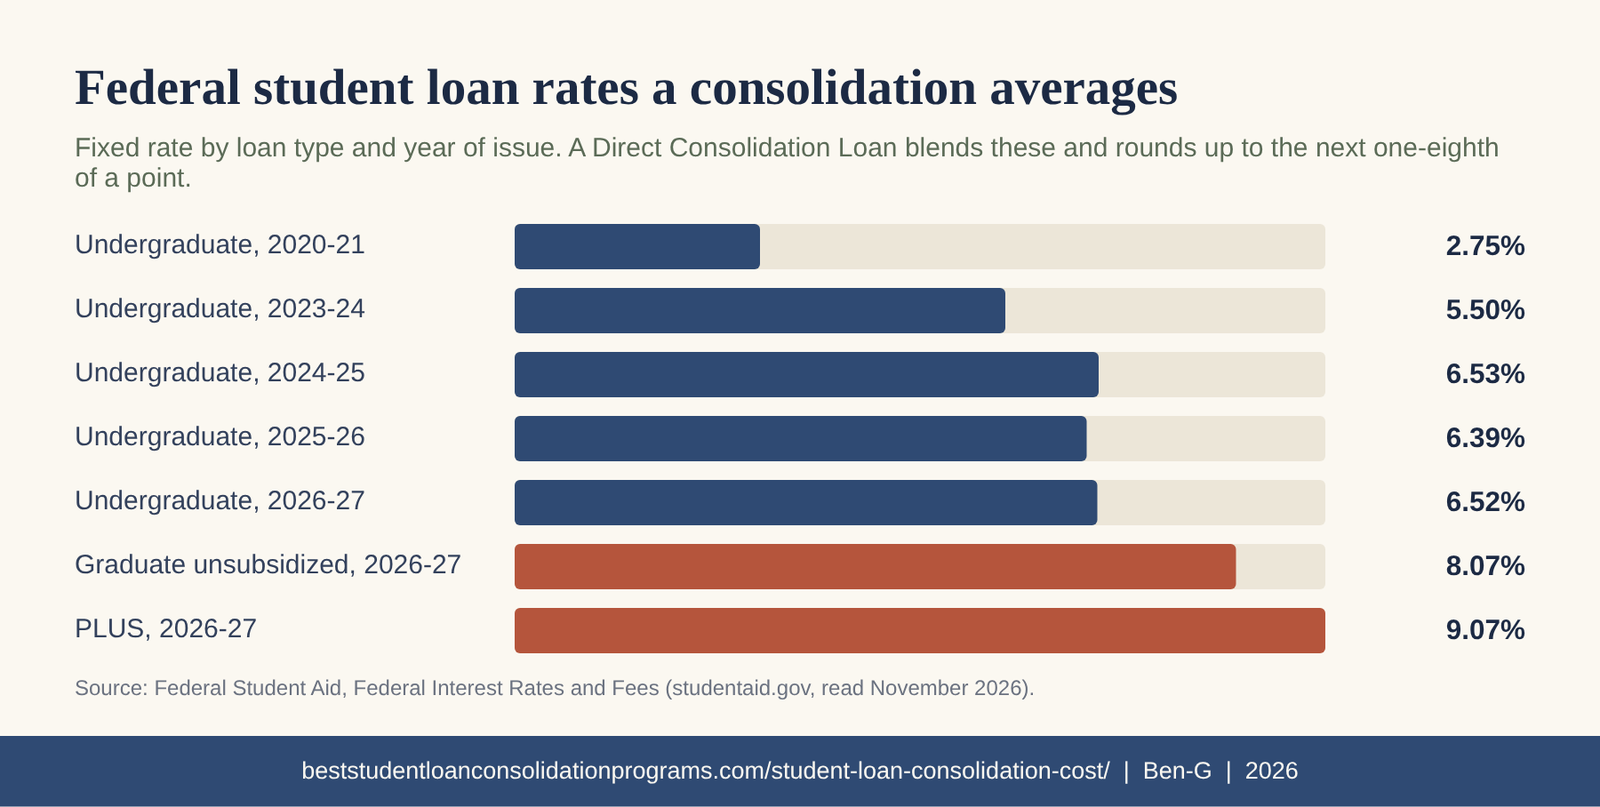
A consolidation blends whatever fixed rates your loans already carry. Loans issued for 2026-27 carry 6.52% for undergraduates, 8.07% for graduate students and 9.07% for PLUS (Federal Student Aid, 2026). Undergraduate loans from 2020-21 carry 2.75%. Mixing cheap old loans with expensive new ones locks the blend in for good.
| METRIC | VALUE | SOURCE |
|---|---|---|
| Undergraduate Direct, 2026-27 | 6.52% | Federal Student Aid |
| Graduate Direct Unsubsidized, 2026-27 | 8.07% | Federal Student Aid |
| Direct PLUS, 2026-27 | 9.07% | Federal Student Aid |
| Undergraduate Direct, 2025-26 | 6.39% | Federal Student Aid |
| Undergraduate Direct, 2024-25 | 6.53% | Federal Student Aid |
| Undergraduate Direct, 2023-24 | 5.50% | Federal Student Aid |
| Undergraduate Direct, 2020-21 | 2.75% | Federal Student Aid |
The spread between years is the hidden fourth cost. Separate loans let you send every extra dollar to the most expensive one; a borrower holding a 2.75% loan and a 6.52% loan can attack the second and leave the first alone. After consolidation there is one loan at one blended rate, and that targeting is gone. Nothing in the weighted average is lost on paper, but the fastest payoff strategy is.
This is also where consolidation and refinancing part ways. Consolidation keeps the loans federal and cannot lower the rate; a private refinance can lower it and removes federal protections permanently. The trade-offs are set out in our student loan refinancing section, including what an application does to your credit score.
The year-by-year table explains why two borrowers with the same balance can face very different consolidations. Someone who borrowed during the pandemic years holds some of the cheapest federal debt ever issued, and blending it with anything newer raises the cost of paying down the cheap portion. Someone whose loans were all issued in the last three years holds rates that sit close together, so the blend changes little and only the round-up applies. Before applying, list each loan with its balance and rate. If the rates are far apart, consider leaving the cheapest loans out of the consolidation, which the application allows. Leaving a loan out preserves its separate rate, but not its repayment plan: once a consolidation loan is made on or after July 1, 2026, the loans you left out are also limited to RAP or the Tiered Standard plan.
5 Is There Still a Cap on Consolidation Rates? Not Since July 1, 2013
No. The regulation capped the consolidation rate at 8.25 percent only for applications received before July 1, 2013 (Code of Federal Regulations, 34 CFR 685.202, 2026). Later applications use the same weighted-average and round-up method with no ceiling, so a blend of 8.07% graduate and 9.07% PLUS loans consolidates above the old cap.
| METRIC | VALUE | SOURCE |
|---|---|---|
| Old rate cap | 8.25 percent | Code of Federal Regulations, 34 CFR 685.202 |
| Applies to applications received before | July 1, 2013 | Code of Federal Regulations, 34 CFR 685.202 |
| Cap on current applications | None | Code of Federal Regulations, 34 CFR 685.202 |
| $60,000 graduate plus $40,000 PLUS, weighted average | 8.47% (calculated) | Federal Student Aid |
| Same mix after the round-up | 8.50% (calculated) | Federal Student Aid |
Many older guides, and some university aid pages that have not been edited in a decade, still quote the cap as if it were live. It is not, and the difference matters most for graduate and parent borrowers, whose loans are issued above eight percent in the current year. A parent consolidating PLUS loans alone simply keeps the PLUS rate, rounded up, but a consolidation made on or after July 1, 2026 that includes a parent PLUS loan can be repaid only under the Tiered Standard plan: no income-driven plan and no PSLF (20 U.S.C. 1087e(d)(7)(E)).
Put together, the ranking is consistent across every balance we tested: the longer term costs the most dollars, capitalized interest comes second, and the round-up that gets all the attention comes last. Since July 1, 2026 the loss of older repayment plans can outweigh all three. The first two dollar costs are largely avoidable with one payment before applying and one decision about how much to pay each month. More on the mechanics is filed under Direct Consolidation.
Explore every figure in this article
Methodology
Figures marked as calculated are our own level-payment amortization arithmetic on the inputs cited in the same row; every other figure is quoted from the linked source. Rates, the regulation and Federal Student Aid’s example were checked on November 14, 2026; the Tiered Standard terms were updated on November 16, 2026. Federal Student Aid’s interest-rate and definitions pages load only in a browser, so the rates and the Tiered Standard terms were read there directly on the same day. Calculations assume fixed rates and on-time level payments and do not model income-driven plans.
Frequently Asked Questions
Does consolidating federal student loans lower your interest rate?
No. A Direct Consolidation Loan uses the weighted average of the rates on the loans you combine, rounded up to the nearest one-eighth of one percent, and the result is fixed for the life of the loan. The new rate is therefore equal to or slightly above what you were already paying on average, never below it. (Federal Student Aid, 2026)
How much does interest capitalization add when you consolidate?
It depends on how much unpaid interest you carry in. In Federal Student Aid's example, $3,890 of unpaid interest on a $27,000 loan raises the monthly payment from $193 to $221 and the 20-year total from $46,425 to $53,113. Paying accrued interest before you apply avoids the interest-on-interest, though you still pay the interest itself and some accrues while the application is processed. (Federal Student Aid, 2026)
Is there a cap on Direct Consolidation Loan interest rates?
Not for current applications. The regulation capped the rate at 8.25 percent only for consolidation applications received before July 1, 2013. Applications since then use the same weighted-average and round-up method with no ceiling, so combining graduate and PLUS loans can produce a rate above the old cap. (Code of Federal Regulations, 34 CFR 685.202, 2026)
What rates does a 2026 consolidation average together?
Whatever fixed rates your existing loans already carry. Loans first disbursed in 2026-27 were issued at 6.52% for undergraduates, 8.07% for graduate students and 9.07% for PLUS borrowers, while undergraduate loans from 2020-21 carry 2.75%. Consolidating keeps the dollar-weighted blend of those rates and locks it in. (Federal Student Aid, 2026)
Does consolidation make repayment longer?
It can. A consolidation made on or after July 1, 2026 uses the Tiered Standard plan or RAP; Tiered Standard sets terms from 10 to 25 years by total Direct Loan principal (15 years for $25,000 to $49,999), which lowers the monthly bill and raises total interest. Federal Student Aid’s older example used 20 years. (Federal Student Aid, 2026)
Can you undo a federal consolidation?
No. Federal Student Aid states that once loans are combined into a Direct Consolidation Loan the consolidation cannot be undone. The rounded-up rate, any capitalized interest and the loss of separate loans are permanent, so the capitalization cost in its example is worth avoiding before you sign. (Federal Student Aid, 2026)
Sources & References
- Federal Student Aid. “5 Things to Know Before Consolidating Federal Student Loans.” studentaid.gov/articles/5-things-before-consolidating-student-loans/. Accessed 2026-11-14.
- Code of Federal Regulations, 34 CFR 685.202. “34 CFR 685.202 – Charges for which Direct Loan Program borrowers are responsible.” ecfr.gov/current/title-34/subtitle-B/chapter-VI/part-685/subpart-B/section-685.2. Accessed 2026-11-14.
- Federal Student Aid. “Federal Interest Rates and Fees.” studentaid.gov/understand-aid/types/loans/interest-rates. Accessed 2026-11-14.
- Federal Student Aid. “One Big Beautiful Bill Act: Important Definitions.” studentaid.gov/announcements-events/big-updates/definitions. Accessed 2026-11-14.
This article is general information for U.S. student loan borrowers, not financial or legal advice. The author is not a lawyer. Confirm details with your loan servicer or studentaid.gov before acting; you remain responsible for your own decisions.
Last updated:

2 Comments
Comments are closed.