Tiered Standard Repayment Plan Payment Chart (2026): Terms, Edges and RAP
KEY TAKEAWAYS
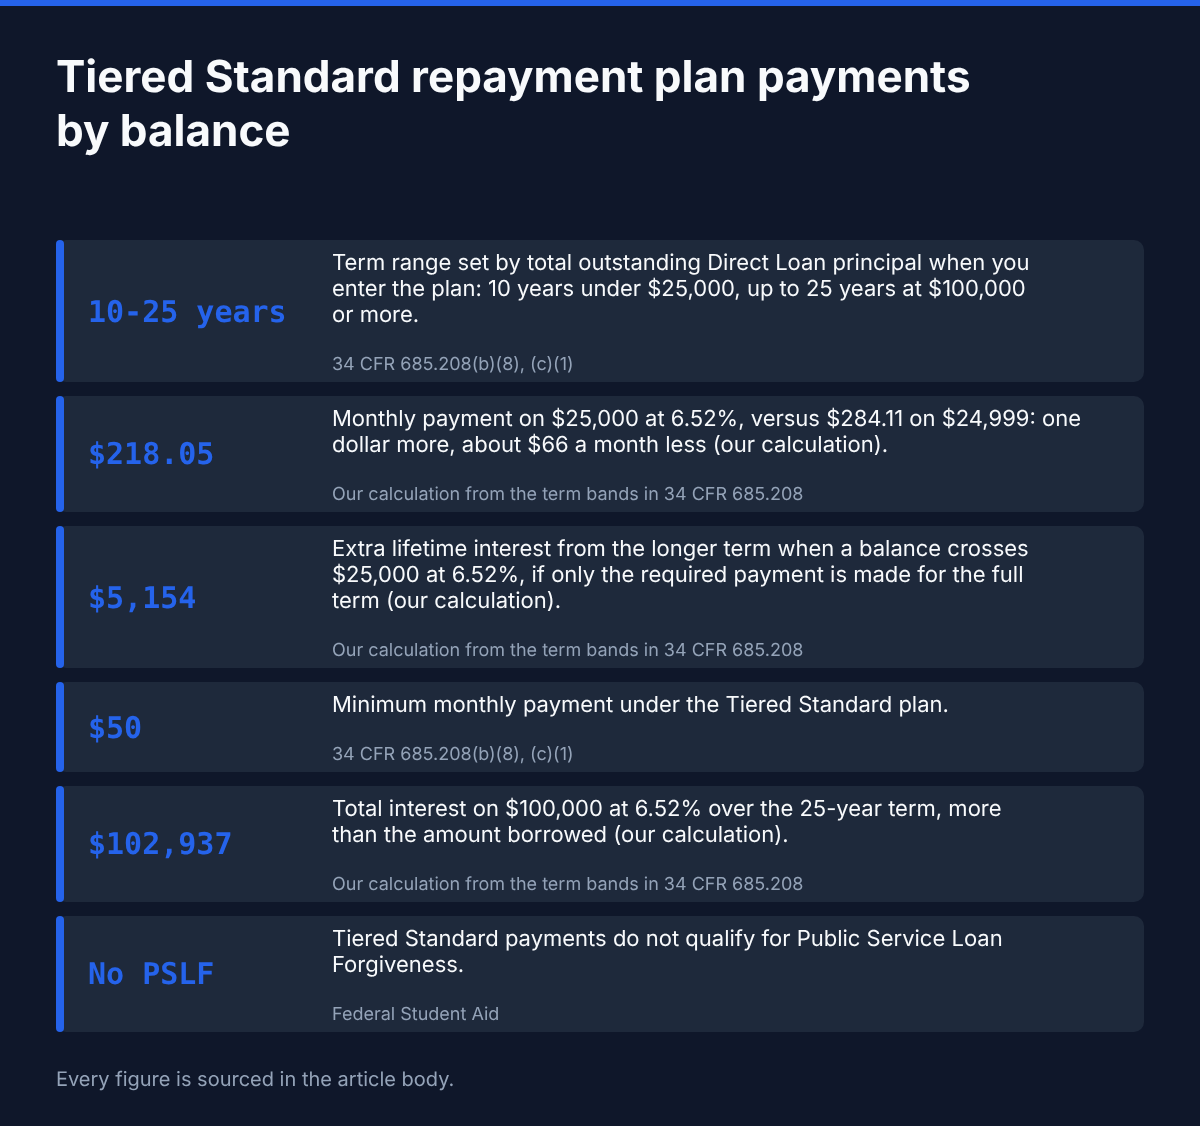
- → 10-25 years Term range set by total outstanding Direct Loan principal when you enter the plan: 10 years under $25,000, up to 25 years at $100,000 or more. (34 CFR 685.208(b)(8), (c)(1), 2026)
- → $218.05 Monthly payment on $25,000 at 6.52%, versus $284.11 on $24,999: one dollar more, about $66 a month less (our calculation). (Our calculation from the term bands in 34 CFR 685.208, 2026)
- → $5,154 Extra lifetime interest from the longer term when a balance crosses $25,000 at 6.52%, if only the required payment is made for the full term (our calculation). (Our calculation from the term bands in 34 CFR 685.208, 2026)
- → $50 Minimum monthly payment under the Tiered Standard plan. (34 CFR 685.208(b)(8), (c)(1), 2026)
- → $102,937 Total interest on $100,000 at 6.52% over the 25-year term, more than the amount borrowed (our calculation). (Our calculation from the term bands in 34 CFR 685.208, 2026)
- → No PSLF Tiered Standard payments do not qualify for Public Service Loan Forgiveness. (Federal Student Aid, 2026)
The Tiered Standard plan is one of the two plans for federal borrowers with a Direct Loan first disbursed on or after July 1, 2026; the other is the Repayment Assistance Plan (RAP). Its term is not a flat 10 years: it runs 10 years, 15 years, 20 years or 25 years depending on your total outstanding Direct Loan principal when you enter the plan (34 CFR 685.208(b)(8), (c)(1), 2026). Because the term jumps at fixed balances, crossing $25,000 by a single dollar lowers the monthly payment and, if only the required payment is made for the full term, adds about $5,154 of interest at today’s undergraduate rate (our calculation).
This page gives the payment and total interest for common balances at the 2026-27 rates, shows the three band edges, and compares the plan with RAP. For how RAP itself is calculated, see our RAP payment table by income.
This page is general information only. It is not legal, tax or financial advice, the author is not a lawyer, and you remain responsible for your own decisions. Your servicer’s figures depend on your actual loans and rates, so check them in your studentaid.gov account or with your servicer before choosing a plan.
1 What Is the Tiered Standard Plan and Who Is on It?
It is a fixed-payment plan whose term is set by your total outstanding Direct Loan principal when you enter the plan, from 10 years to 25 years, with a minimum payment of $50 (34 CFR 685.208(b)(8), (c)(1), 2026). Borrowers with a Direct Loan first disbursed on or after July 1, 2026 choose between it and RAP (20 U.S.C. 1087e(d)(7), 2026).
| TOTAL OUTSTANDING DIRECT LOAN PRINCIPAL WHEN YOU ENTER THE PLAN | TERM | SOURCE |
|---|---|---|
| Under $25,000 | 10 years | 34 CFR 685.208(b)(8), (c)(1) |
| $25,000 to under $50,000 | 15 years | 34 CFR 685.208(b)(8), (c)(1) |
| $50,000 to under $100,000 | 20 years | 34 CFR 685.208(b)(8), (c)(1) |
| $100,000 or more | 25 years | 34 CFR 685.208(b)(8), (c)(1) |
The statute counts the total outstanding principal of all your Direct Loans, made before, on or after July 1, 2026 (20 U.S.C. 1087e(d)(7), 2026), and Federal Student Aid says the term is set by the principal you owe when you enter the plan (Federal Student Aid, 2026). The statute and Federal Student Aid both refer to outstanding principal, so accrued unpaid interest may not count toward the threshold even though you still owe it; the regulation says only “total amount of Direct Loans,” so near an edge, confirm with your servicer which side you fall on. The term is recalculated if you add loans later or leave the plan and return, and the new term is based on your total outstanding principal at that point (Federal Student Aid, 2026).
Once a loan first disbursed on or after July 1, 2026 enters repayment, all of your Direct Loans, including older ones, must be repaid under the Tiered Standard plan or RAP (Federal Student Aid, 2026). Borrowers who choose neither are placed on the Tiered Standard plan (20 U.S.C. 1087e(d)(7), 2026). Parent PLUS loans, and consolidations that repaid one, can use only this plan once the borrower has such a new loan, as our Parent PLUS deadline guide explains.
The plan has no income test and no forgiveness at the end; the loan is paid off over the term. Federal Student Aid lists it among plans whose payments do not qualify for Public Service Loan Forgiveness (Federal Student Aid, 2026). Of the two plans available after a new loan, only RAP payments can count, and you can switch from the Tiered Standard plan to RAP at any time (20 U.S.C. 1087e(d)(7)(D), 2026), except for parent PLUS loans and consolidations that repaid one; only payments made after the switch can count. Our PSLF payment count guide covers how qualifying payments are counted.
2 How Much Is the Tiered Standard Payment? Chart by Balance at 2026-27 Rates
At the 2026-27 undergraduate rate of 6.52% (Federal Student Aid, 2026), the payment runs from about $114 a month on $10,000 to about $1,015 on $150,000 (our calculation). Total interest grows faster than the payment because the term lengthens: about $17,099 on $30,000, $47,532 on $60,000 and $102,937 on $100,000.
| BALANCE | TERM | MONTHLY AT 6.52% | TOTAL INTEREST AT 6.52% | MONTHLY AT 8.07% | MONTHLY AT 9.07% |
|---|---|---|---|---|---|
| $10,000 | 10 years | $113.65 | $3,638 | $121.70 | $127.05 |
| $20,000 | 10 years | $227.30 | $7,276 | $243.40 | $254.11 |
| $30,000 | 15 years | $261.66 | $17,099 | $287.91 | $305.53 |
| $40,000 | 15 years | $348.88 | $22,799 | $383.88 | $407.37 |
| $60,000 | 20 years | $448.05 | $47,532 | $504.48 | $542.54 |
| $75,000 | 20 years | $560.06 | $59,415 | $630.60 | $678.17 |
| $100,000 | 25 years | $676.46 | $102,937 | $776.46 | $844.00 |
| $125,000 | 25 years | $845.57 | $128,672 | $970.57 | $1,054.99 |
| $150,000 | 25 years | $1,014.69 | $154,406 | $1,164.69 | $1,265.99 |
The three rate columns use the 2026-27 fixed rates for undergraduate Direct Loans (6.52%), graduate unsubsidized loans (8.07%) and PLUS loans (9.07%) (Federal Student Aid, 2026); new Grad PLUS loans are limited to students covered by the interim exception. Real balances usually mix loans from different years at different rates, so treat the table as a range rather than a quote; a consolidation loan’s rate is a weighted average rounded up to the next one-eighth of a percent.
Compared with the old 10-year standard plan, the longer terms cut the payment and raise the cost. On $60,000 at 6.52 percent, 10 years would mean about $681.90 a month and $21,828 of interest; the 20-year Tiered Standard term means $448.05 a month and $47,532 of interest (our calculation). The monthly saving of about $234 costs about $25,704 over the life of the loan if only the required payment is made.
Graduate borrowers feel the longer terms most, because their balances and rates are both higher. A $75,000 balance at the graduate rate of 8.07 percent costs about $630.60 a month over 20 years, against about $560.06 at the undergraduate rate, a difference of roughly $16,900 in total interest over the term (our calculation). The same trade-off, a lower bill now and more interest later, runs through our consolidation cost guide.
3 What Happens at the $25,000, $50,000 and $100,000 Edges?
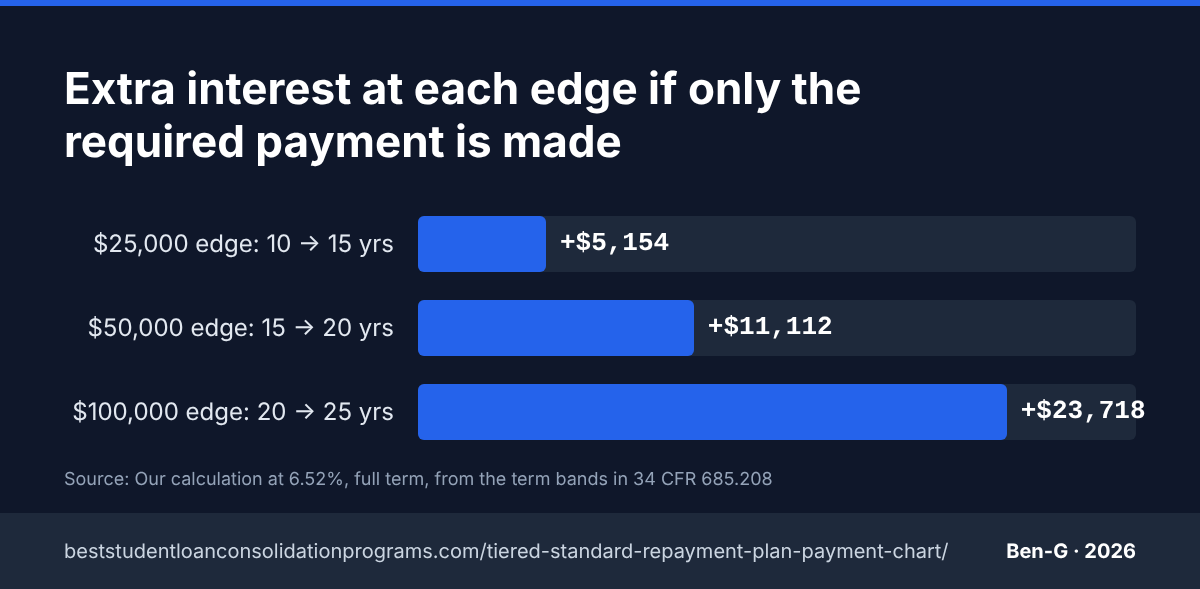
At each edge the term jumps by five years, so a balance one dollar higher gets a lower required payment and, if only that payment is made, much more interest. At 6.52 percent, $24,999 costs $284.11 a month over 10 years and $25,000 costs $218.05 over 15 years, with about $5,154 more interest over the full term (our calculation).
| BALANCE PAIR | MONTHLY PAYMENT | TOTAL INTEREST | DIFFERENCE (OUR CALCULATION) |
|---|---|---|---|
| $24,999 (10 yrs) vs $25,000 (15 yrs) | $284.11 vs $218.05 | $9,095 vs $14,249 | $66 a month less, $5,154 more interest |
| $49,999 (15 yrs) vs $50,000 (20 yrs) | $436.09 vs $373.38 | $28,498 vs $39,610 | $63 a month less, $11,112 more interest |
| $99,999 (20 yrs) vs $100,000 (25 yrs) | $746.74 vs $676.46 | $79,219 vs $102,937 | $70 a month less, $23,718 more interest |
The edges work in both directions. A borrower just above $25,000 gets a lower required payment than a borrower just below it, which can help a tight budget, but pays for that relief in interest if the loan runs its full term: $5,154 at the first edge, $11,112 at the second and $23,718 at the third, all at 6.52 percent (our calculation).
The longer term is a ceiling, not a requirement. Direct Loans carry no prepayment penalty (34 CFR 685.211(a)(2), 2026), so a borrower on a 15-year term who pays the 10-year amount each month finishes early and avoids most of the extra interest. By default, an extra payment at least as large as your monthly payment pushes back your next due date; if you want to keep paying every month and finish sooner, ask your servicer not to advance it.
Because the term is recalculated when you add loans or leave the plan and return (Federal Student Aid, 2026), a later loan, or a return after paying down below an edge, can move you to a longer or a shorter term. Before you borrow again or switch plans, ask your servicer which principal and start date it used; that is a reason to check, not a reason to borrow more or less than you need.
4 When Is RAP Lower? Income Crossovers for a Single Borrower at 6.52%
For a single filer with no dependents, RAP’s monthly payment stays below the Tiered Standard payment up to about $60,000 of income on a $30,000 balance, about $76,800 on $60,000 and about $90,200 on $100,000, all at 6.52 percent (our calculation). Above those incomes the Tiered Standard payment is lower.
| BALANCE AT 6.52% | TIERED STANDARD MONTHLY | RAP IS LOWER UP TO ABOUT (SINGLE, NO DEPENDENTS) | SOURCE |
|---|---|---|---|
| $30,000 | $261.66 | $60,000 of AGI | Our calculation, 20 U.S.C. 1087e(q) |
| $60,000 | $448.05 | $76,800 of AGI | Our calculation, 20 U.S.C. 1087e(q) |
| $100,000 | $676.46 | $90,200 of AGI | Our calculation, 20 U.S.C. 1087e(q) |
RAP charges 1 to 10 percent of adjusted gross income depending on the band, minus $50 a month per dependent, with a $10 minimum; married borrowers who file jointly are measured on combined income. Our RAP guides set out the formula. Dependents push the crossover higher: with one dependent, RAP stays below the Tiered Standard payment on $30,000 up to about $62,300 of income, and on $60,000 up to $80,000 (our calculation). A raise pushes RAP up in steps while the Tiered Standard payment stays fixed, so the income you expect over the next several years matters more than this year’s.
Monthly payment is not the whole comparison. Under RAP, unpaid interest is not charged after an on-time payment, the Secretary adds a principal match of up to $50 a month, capped at the amount paid, and the remaining balance is cancelled after 360 qualifying payments (20 U.S.C. 1087e(q)). The Tiered Standard plan has none of those features but usually ends sooner, and of the two plans only RAP counts for PSLF (Federal Student Aid, 2026).
Borrowers whose loans were all made before July 1, 2026 keep older options such as Income-Based Repayment as well as RAP (not available for parent PLUS loans), though ICR and PAYE end no later than July 1, 2028. For them, taking a new loan, including a new Direct Consolidation Loan, is the decision that sets which plans remain.
5 Does Consolidating or Borrowing Again Put You on the Tiered Standard Plan?
It can. A consolidation loan made on or after July 1, 2026 can be repaid only under the Tiered Standard plan or RAP (20 U.S.C. 1087e(g)(3)), and once a loan first disbursed on or after that date enters repayment, all of your Direct Loans must be repaid under one of those two plans (Federal Student Aid, 2026).
| SITUATION | PLANS AVAILABLE | SOURCE |
|---|---|---|
| All loans made before July 1, 2026, no new loan | Older plans, including IBR, plus RAP (not for parent PLUS loans) and Tiered Standard; ICR and PAYE end by July 1, 2028 | studentaid.gov |
| Any Direct Loan first disbursed on or after July 1, 2026, once it enters repayment | Tiered Standard or RAP, for all your Direct Loans | 20 U.S.C. 1087e(d)(7); studentaid.gov |
| Direct Consolidation Loan made on or after July 1, 2026 | Tiered Standard or RAP | 20 U.S.C. 1087e(g)(3) |
| Parent PLUS loan, or a consolidation that repaid one, if you have any Direct Loan made on or after July 1, 2026 | Tiered Standard only | 20 U.S.C. 1087e(d)(7)(C), (E); studentaid.gov |
| No plan chosen | Tiered Standard, assigned by the Department | 20 U.S.C. 1087e(d)(7)(B) |
This is why a consolidation or a small new loan can have consequences far larger than its own balance: it changes the plan options on every Direct Loan the borrower holds. Our federal loan consolidation section follows those rules as the Department publishes guidance.
Borrowers can switch between the Tiered Standard plan and RAP at any time, in either direction (20 U.S.C. 1087e(d)(7)(D)); parent PLUS loans and consolidations that repaid one are the exception and must stay on the Tiered Standard plan (20 U.S.C. 1087e(d)(7)(E)). Some servicer and summary pages describe these rules differently, so confirm any switch with your servicer in writing, and remember that switching back into the Tiered Standard plan recalculates its term.
For a borrower who will end up on the Tiered Standard plan, the numbers that matter are the term your principal triggers, the payment at your actual rates and how much extra interest the longer term adds. Your servicer and your studentaid.gov account show your actual loans and rates. Paying more than the required amount reduces the extra interest a longer term adds.
Explore every figure in this article
Methodology
Plan rules come from 34 CFR 685.208 and 685.211 and 20 U.S.C. 1087e on Cornell’s Legal Information Institute, the final rule at 91 FR 23768, and Federal Student Aid’s OBBBA, definitions and PSLF pages, read on November 17, 2026. Payments are our own level-payment amortization at the 2026-27 fixed rates (6.52, 8.07 and 9.07 percent); total interest uses the unrounded payment, so servicer figures can differ by a few dollars, and edge differences are computed from the rounded totals shown. RAP payments follow 20 U.S.C. 1087e(q) for a single (unmarried) filer with no dependents, plus a one-dependent case in section 4.
- Sources consulted: 8
- Sources cited: 8
- Data range: 2026-05-01 to 2026-11-17
- Research date: 2026-11-17
- Update schedule: When the Education Department publishes new rates (each July) or changes the Tiered Standard rules
- Limitations: Payments are our own level-payment calculations at the 2026-27 fixed rates; real loans mix rates from different years, so your servicer's figure will differ. Edge differences are computed from the rounded totals shown. RAP comparisons assume a single (unmarried) filer with no dependents, plus a one-dependent case, and ignore RAP's interest waiver and principal match, which change total cost.
Frequently Asked Questions
What is the Tiered Standard repayment plan?
A fixed-payment federal plan. Borrowers with a Direct Loan first disbursed on or after July 1, 2026 choose between it and RAP. The term depends on your total outstanding Direct Loan principal when you enter the plan: 10 years under $25,000, 15 years from $25,000, 20 years from $50,000 and 25 years from $100,000, with a $50 minimum payment. The term is recalculated if you add loans or leave the plan and return. (34 CFR 685.208, 2026)
How much is the Tiered Standard payment on $30,000?
At the 2026-27 undergraduate rate of 6.52 percent, $30,000 over the 15-year term is about $261.66 a month, with about $17,099 in total interest (our calculation). Your servicer's figure depends on your actual rates and balance. (Our calculation, 2026)
Does the Tiered Standard plan count for PSLF?
No. Federal Student Aid lists the Tiered Standard plan among plans that do not qualify for PSLF. Of the two plans available after a new loan, only RAP payments can count. You can switch from the Tiered Standard plan to RAP at any time, except for parent PLUS loans and consolidations that repaid one; only payments made after the switch can count. (Federal Student Aid, 2026)
Can I pay more than the Tiered Standard payment?
Yes. Direct Loans can be prepaid at any time without penalty. By default, an extra payment at least as large as your monthly payment pushes back your next due date; if you want to keep paying every month and finish sooner, ask your servicer not to advance it. (34 CFR 685.211, 2026)
Who is placed on the Tiered Standard plan?
Borrowers with a Direct Loan made on or after July 1, 2026 choose between the Tiered Standard plan and the Repayment Assistance Plan; those who do not choose are placed on the Tiered Standard plan. If you have a loan made on or after July 1, 2026, parent PLUS loans and consolidations that repaid one can use only the Tiered Standard plan. Other loans can switch between the two plans at any time. (20 U.S.C. 1087e(d)(7), 2026)
Sources & References
- Federal Student Aid. “One Big Beautiful Bill Act: Important Definitions (updated Oct. 30, 2026).” studentaid.gov/announcements-events/big-updates/definitions. Accessed 2026-11-17.
- Federal Student Aid. “Public Service Loan Forgiveness.” studentaid.gov/manage-loans/forgiveness-cancellation/public-service. Accessed 2026-11-17.
- Federal Register. “Final regulations, 91 FR 23768 (May 1, 2026).” federalregister.gov/documents/2026/05/01/2026-08556/reimagining-and-improving-st. Accessed 2026-11-17.
- Legal Information Institute (CFR). “34 CFR 685.208 Fixed payment repayment plans (as amended May 1, 2026).” law.cornell.edu/cfr/text/34/685.208. Accessed 2026-11-17.
- Legal Information Institute (U.S. Code). “20 U.S. Code 1087e – Terms and conditions of loans.” law.cornell.edu/uscode/text/20/1087e. Accessed 2026-11-17.
- Legal Information Institute (CFR). “34 CFR 685.211 Miscellaneous repayment provisions.” law.cornell.edu/cfr/text/34/685.211. Accessed 2026-11-17.
- Federal Student Aid. “Federal Interest Rates and Fees.” studentaid.gov/understand-aid/types/loans/interest-rates. Accessed 2026-11-17.
- Federal Student Aid. “One Big Beautiful Bill Act Updates.” studentaid.gov/announcements-events/big-updates. Accessed 2026-11-17.
Last updated:

2 Comments